
Articles
Filter by: Date, Finance, Inheritance, Litigation, Property, Rental, Residency, Taxation, Uncategorized

How to Apply for Healthcare in Spain
Raymundo Larraín Nesbitt, November, 8. 2014
Expats retiring to Spain will need to consider health care along with property rental or investment decisions. Regular legal-contributor Raymundo Larraín Nesbitt strays again from his usual property themes to give us a general overview on how to apply for healthcare in Spain.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
8th of November 2014
Emergency Cover vs. Full Healthcare Cover
I have to begin by distinguishing two types of health cover.
- Emergency cover is universal and open to all human beings, whether EU citizens or not. The only requirement for emergency health assistance is that you need to be registered at your local town hall (‘Certificado de Empadronamiento’ or census certificate). This is explained in detail in a section below.
- Access to full health care cover by the Spanish Healthcare System requires a Social Security Number (‘Número de la Seguridad Social’ or SSN for short). This allows you unrestricted access to state-run healthcare. A SSN can be attained by working for a company or else on becoming self-employed (by contributing monthly to a pay-in scheme).
1. Emergency Healthcare Cover
A registered person will have access to public emergency, primary and speciality care for common illness, maternity care during pregnancy, delivery, post-partum etc. It is highly recommended that all foreigners register at their local town hall (known in Spanish as ‘empadronamiento’) for this and many other advantages listed below (and it’s free). Basically the more people that are registered, the more funds the central government allocates to a town hall which – in theory – should benefit everyone.
Step-by-Step Explanation to Attain a Public Health Card (PHC)
A PHC grants you the right to health care (both primary and outpatient) in both hospitals and emergency centres.
1. As outlined, the first step is to attain a Registration Certificate (‘Certificado de Empadronamiento’) from your town hall. This is a pretty straightforward hassle-free requirement. To register oneself at your local town hall simply follow the below:
• EU members: identity document from your own country, Community card issued by a police station or else your passport. Copy of Title Deeds and a copy of a utility bill (water or electricity).
• Tenants: your rental contract, a copy of a utility bill under the name of the tenant (which must match the tenancy agreement) as well as an identity card or passport.
• Home owners: copy of the title deed and/or a utility bill for the property.
• Under aged: if a child lacks a passport they will require the same documents as an adult except for those born in Spain (a birth certificate or Family Book will suffice in such a case).
2. Find out where your Primary Care Centre (‘Centro de Salud’) is located.
3. Take your passport (and a photocopy) together with your Registration Certificate.
4. Fill in the ad hoc form. After a period spanning normally 2 to 3 months you will be mailed your Personal Health Card.
Benefits of Registering Oneself at Your Local Town Hall (Empadronamiento)
I am digressing a bit here from the article’s topic but I feel compelled to explain the benefits of enrolling in your town hall’s census (‘Empadronamiento’ or Registration Certificate):
• Discounts on IBI tax (akin to the United Kingdom’s Council tax). In some municipalities (i.e. Estepona) this discount may reach up to 80% (!).
• Increased medical attention (more doctors).
• More fire-fighters.
• The right to State education (free, public).
• The right to vote (registered foreigners can vote only on local and European elections).
• Discounts on municipal services.
• Free access to Sports Centres.
• Free access to public libraries.
• Access to Social Services and Leisure Centres (full or partial rebates on social activities i.e. painting, music, theatre, sewing).
• Additional security.
• More ambulances.
• More schools.
• Social assistance.
2. Full Cover Health Assistance
As explained in the article’s introduction, for comprehensive cover you must attain a Social Security Number and be working (legally) in Spain. This can be attained either of two ways:
a) By working for someone else i.e. a company.
b) On becoming self-employed (‘autónomo’ in Spanish).
Either requires that you, or your employer on your behalf, contribute to a monthly state pay-in scheme.
European Healthcare Insurance Card (EHIC)
If you are visiting Spain temporarily, and reside mainly in a EEA member country, the EHIC allows you full access to Spain’s State Healthcare System. You must request information in your home country on how to apply for this card.
The EHIC will not be valid if the holder is mainly resident in Spain. It does not cover you either if you are travelling with the express purpose to seek medical treatment i.e. travel to Spain specifically to give birth.
UK State Pensioner
As a UK pensioner, if you are living in Spain and you receive a UK State Pension or long-term Incapacity Benefit, you may be entitled to state healthcare paid for by the UK.
The UK’s EHIC is only for use outside of Spain on holidaymaking within the EU; it is not intended for those whose main abode is in Spain.
Applying for Healthcare in Spain – Conclusion
Foreigners are entitled to the same healthcare as the rest of Spanish citizens. The only requirement is to be registered at the town hall of your residence.
For full health care cover it is mandatory that you attain a Social Security Number and contribute to a monthly state pay-in scheme.
UK pensioner’s access to the Spanish healthcare assistance is paid for by the UK.
“Tres cosas tiene la vida: salud, dinero y amor” – Cristina and Los Stop.
Popular Spanish pop song from the sixties. Loosely translated as: “Only three things matter in life: health, money and love.”
Related articles
- Healthcare in Spain – Advice by the Foreign & Commonwealth Office (UK Government)
- Health Insurance and Social Security – Angloinfo Expat Network
- How to Apply for Healthcare in Spain – 8th November 2014
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.

How to Buy Property in Spain Safely
Raymundo Larraín Nesbitt, October, 10. 2014
Buying property in Spain safely, by solicitor Raymundo Larraín Nesbitt, is an article that provides a trove of information; it will help you clear the minefield and avoid the most common pitfalls. It acts as a compendium on his five-part series ‘How to Buy Property in Spain’. You may also be interested in reading Buying Resale in Spain, Buying Off-Plan Property in Spain, Buying Distressed Property in Spain, How to Buy Commercial Property in Spain or How to Buy Rural Property in Spain.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
10th of October 2014
Introduction
Over the last decade I have written a series of specialized articles featuring real estate conveyance that acted like jigsaw pieces. The purpose of this pretentiously-titled article is to collate part of my dispersed writings on the same topic and group them altogether acting as a backbone that binds and fleshes them out cohesively in a single document. The individual jigsaw pieces should now fall neatly into place forming, one hopes, the overall conveyance puzzle I had in mind.
Following on the above, for reasons of space constraint, I cannot reproduce in this article the hundreds of pages I have written on the matter over the course of years. The idea behind this article is to act as a placeholder repository that conveys basic information on a wide range of conveyance matters and most significantly provides the links to the focused articles which are the ones that really provide in-depth cover on any given subject. So please kindly bear with me and follow the external blue links to the dedicated articles when you want to delve deeper into a topic.
2014 Overview of Spain’s Real Estate Market – A Silver Lining
After seven years of recession I believe we may be almost out of the woods. 2014 in my opinion will be remembered as marking the inflection point where the market started to pick up again and a new property cycle began.
Granted there is still a huge oversupply of properties that will likely take several years to be absorbed by the market. Spain in the boom years built in frenzy more properties than France, Germany and the United Kingdom altogether. This irresponsible glut of properties is largely explained as a result of a combination of factors such as ultra-low interest rates which fostered widespread easy credit, unbridled lender ambition, bloated property valuations commingled with the Administration’s oversight. Properties with poor location and lack of amenities (particularly those found inland) will likely not sell as no one is interested in them irrespective of price. They should have never been built in the first place as they appeal neither to foreign nor domestic demand
What is holding back recovery to a large extent is the credit shortage or credit-crunch. Lenders are being over-conservative handing out mortgages and are enforcing strict lending criteria as many are still widely viewed by experts as undercapitalised. Fortunately the European Central Bank has in a surprising move lowered the base rate last September to a historical low of 0.05%. This is a welcome respite for mortgage borrowers (maybe not so much for Germany) which may in time help credit to flow back to families and society at large. Albeit being realistic this new base rate will not translate to an immediate availability of credit and is likely to take quite some time to permeate through. But it is most certainly a step in the right direction. This bold move by the ECB suggests interest rates across the Eurozone will remain at historical lows for some time allowing buyers of second homes to take advantage of competitive rates.
Credit is the lifeblood of the real estate market; without mortgage financing the market languishes and grinds to a halt relying heavily on cash-buyers which are obviously a minority. Encouraging signs of lenders willing to lend again, with reasonable terms, are beginning to hit the headlines. Affordable borrowing will play a major role in the rebound as it is a prerequisite to a solid housing market recovery.
The overall outlook is that there is still a massive glut of properties available but what’s important to note is that the market is multi-tiered and we are witnessing recovery at different speeds much the same as Europe offers countries with variable growth levels. The high-end of the spectrum, dominated by premium properties, is selling quickly once again. As in every recovery in Spain the rebound is kick started by well-heeled buyers acquiring high-end properties. The drive sparked by top-of-the-range real estate will eventually gain momentum to the point of pushing forward the mid-range market in a herd mentality. This is how every recovery in Spain has begun and I believe we are precisely at a cycle turning point with well-off clients seizing first-rate properties with the general market to follow trend in due course.
For the first time in several years reports are surfacing pointing to a fledgling house price recovery. Even Spain’s National Statistic Bureau (INE) has joined in reporting the first house price increase in a six-year period. What it is clear to my mind is that the market has indeed levelled off and we are now well on track on the road to recovery with well-located and smartly-priced properties gaining traction.
Any industry insider will tell you that we have witnessed in 2014 – for the first time in seven years – strong foreign demand mainly from north European countries (Nordics), Russians and to a lesser extent Arabs. Domestic demand remains depressed conditioned by all-time high borrowing costs with the exception of high-end property which has proved resilient with affluent Spaniards from Madrid and the Basque country (let alone wealthy foreigners) snatching up trophy properties at bargain prices in well-to-do locations.
A traditional indicator of recovery in Spain has been when savvy wealthy Spanish families buy into the market decisively which is indicative of a cycle end and the beginning of a new one as witnessed over the last two property cycles (eighties and nineties). Upbeat macro figures are pointing more and more that we could really be at the start of a new growth period. Whether this bourgeoning recovery holds up and translates into consistent growth remains to be seen as external geopolitical factors could easily derail it.
Hire a Qualified Registered Lawyer
This is the single most important advice that can be given before you start house-hunting. If you only happen to follow this first tip the rest of the points mentioned in this article become redundant.
Hiring a lawyer is by no means mandatory on conveyance procedures. But I cannot stress enough the importance of retaining a Spanish lawyer, if you are a foreigner, to act on your behalf in a conveyance procedure, both on buying and selling property. This should be your starting point before signing any reservation agreements or paying any deposits.
It is often that I hear that those with vested interests in their being no lawyers involved are often the most outspoken on advocating that retaining a lawyer’s service is an unnecessary expense and always put as an example that Spaniards themselves don’t hire them on buying property.
Whilst it may be true that some Spaniards do not retain a lawyer to act on their behalf in a conveyance this can be explained for a number of reasons. Almost every Spaniard has a relative or a friend who happens to be a lawyer and advises them free of charge. Besides they are fluent in their own language (!) and have ready access to a myriad of legal articles which are regularly published in the press. Despite this Spaniards still end up having all sorts of problems on buying or selling property because they did not want to incur in additional expenses hiring a professional. Quite often their blunder far exceeds what a lawyer would have charged for his service.
To identify oneself as an “abogado/lawyer” one must be both qualified and registered in Spain:
· Qualified: having passed and attained a Spanish law degree or else by having homologated it.
· Registered: being admitted to practice Law at one of Spain’s regional Bar Associations.
The second point is already inclusive of the first one, as on applying to practice Law before a Bar Association one must submit both his Law degree and his full academic record. Additionally, someone with a criminal record may not join the Law Society. One should exercise extreme caution on those claiming to be an ‘abogado’ and yet are unregistered to practice. Ask yourself why? Quite a few of the notorious mishaps featured in the press relate to non-qualified intruders dealing in conveyance matters.
Besides registered lawyers have the advantage of professional indemnity insurance in the event of negligence or malpractice. Bottom line; make sure your lawyer is registered to practice, for your own sake. Be wary of cold-calling from legal advisors, senior legal advisors, legal executives, legal assistants, paralegals and in general anyone who does not clearly identify himself/herself as a lawyer/abogado (and is therefore registered).
Unlike other countries such as the United Kingdom these fancy titles don’t mean anything in Spain – we have no paralegals. Or you are either a registered Spanish lawyer or you are not, period. It’s that simple. Someone who is not a trained registered lawyer is not qualified to give legal advice in any shape or form, cannot entertain to address himself/herself as a ‘lawyer’, cannot solicit clients for legal services – even if outsourced – nor practice law in Spain. You can easily check if your lawyer is registered to practice law on this registered Lawyer’s database. Beware of the increasing number of Spanish bogus law firms cold-calling requesting money upfront (particularly regarding timeshare). They are not law firms, they are boiler rooms (unlicensed, unregulated and unsupervised).
If the property you wish to buy is high-end you may want to seek advice beforehand so as to mitigate tax exposure, namely to Spanish Inheritance Tax. Often the best tax planning results are achieved prior to acquiring a property as they may require the incorporation of a string of holding companies to lock-up the asset. You can read further in my article: Buying and Owning Spanish Property through Companies: Pros and Cons.
Bottom line it is advisable to retain an independent lawyer in Spain both on buying and selling property.
You can check this list of recommended English-speaking lawyers or request one from your home country’s local consulate in Spain.
NIE Number Requirement
One of the first steps on buying property in Spain, besides hiring a lawyer, is to apply for what is known as a Spanish NIE number which is a Tax Identification Number for foreigners enabling you to file and pay taxes into the Spanish Tax office. It will be required, for example, on all the following:
- Buying or selling property.
- Inheriting assets in Spain.
- Opening a bank account.
- Taking out insurance.
- Buying a car.
- Working in Spain.
- Obtaining a mortgage.
- Some private foreign schools require a NIE number from parents and/or new (foreign) pupils to enrol them!
Basically any activity involving paying taxes requires a NIE number. You cannot complete on a property in Spain without one, either on buying or selling, as the Notary will disallow it.
You may apply for a NIE number in person or else appoint a lawyer to do it on your behalf. Our law firm offers this service: NIE number service.
For the former, be ready to take time off work, allocate holidays, spend over €1,000 in booking flights and hotels to Spain all to wake up very early and make long queues under a scorching sun for hours on end. Did I mention your Spanish must be excellent as public servants will seldom speak in English let alone other languages?
Or alternatively you can cut to the chase using the most popular option which requires appointing a lawyer as a proxy by means of a limited Power of Attorney (P.O.A.) specific only to apply for a NIE number. Lawyers usually charge a reasonable fee of €100 – €150 for it. In under ten days you will have a new NIE number mailed (or e-mailed) to you to get you started on your property hunt.
Property Types
I distinguish broadly between five types of real estate property. The first four may be grouped under the generic term ‘resale’ property whereas the fifth is new-build or off-plan which requires a category all unto itself and for this reason I reserve it the last place below.
I go into the trouble of distinguishing these five categories or subclasses because they each sport their own nuances and idiosyncrasies which ought to be highlighted clearly to would-be buyers so they are fully aware of the differences. In most legal articles dealing with Spanish property conveyance you will find them all grouped together in a mixed bag making no distinction which I honestly believe is a crass mistake. The division is not merely academical but practical.
1. ‘Standard’ Urban Resale Property
Is hands down the most frequent property-type conveyed.
Please read my article Buying Resale Property in Spain.
2. Commercial Property
Is a type of property legally earmarked as commercial premises subject to special taxation and other particularities (i.e. opening licence).
Please read my article How to Buy Commercial Property in Spain.
3. Rural Property
Requires a (cautious) approach to it due to the myriad problems it has caused in the past.
Please read my article How to Buy Rural Property in Spain.
4. Distressed Assets (Fire Sales and Bank Repossessions)
This term refers to pre or post lender repossessions which are rife on the radio and press. The following two articles clearly explain how to profit from distressed real estate assets held by lenders or directly from private owners seeking a quick sale. Fire sales and foreclosures offer great value as they are heavily discounted.
Please read my articles Buying Distressed Property in Spain and Bank Repossessions in Spain.
5. Off-Plan or New-Build Property
As explained above, the fifth type of property cannot be labelled – by definition – as resale and requires a distinct category all unto itself. Off-the-plan or new-build property is when you sign a contract to buy a property that is yet to be built and is not expected to be finished until several years’ time. I strongly recommend reading my articles:
• Buying Off-Plan Property in Spain
• Off-Plan Construction Guarantees
• Bank Guarantees in Spain
• Supreme Court Rulings on Bank Guarantees
• Licence of First Occupation
They provide an insightful account of the full off-plan buying procedure. Due to space constraints I am unable to reproduce the hoard of information available to them. These articles explain key concepts, such as Bank Guarantees and Licence of First Occupation, which are specific to off-plan and not shared by its resale cousins (with the exception of Catalonia where LFO’s are indeed required for resales).
The market has swerved from one extreme to another; from loving off-plan to having a major fallout. In time the market will find its equilibrium. Although nowadays you will find that off-plan is being almost demonised in the press the fact is that buying off-plan has many advantages as well as some associated drawbacks. Not that long ago it was normal to obtain a significant discount (premium) on buying off-plan as you took on a risk until the unit was ready to be delivered legally (with a Licence of First Occupation). The main risks were related to the uncertainty of the property ever being delivered as well as the time elapsed until completion which could easily take two years or more.
Many took advantage in the boom times selling on these properties for a sizeable profit prior to completion (also known as “flipping”) as it was basically a leveraged investment (ultra-low interest rates coupled with lenders’ lax lending criteria fuelled widespread easy credit) which only required a fraction of the funds paid up front. That same off-plan dwelling was significantly more expensive (i.e. 30%) if you purchased it key-ready as now there was no associated risk (uncertainty).
This, however, changed over time leading us onto today’s depressed market. Now that the dust has settled, purchasers are increasingly turning to resale property in lieu of off-plan as they judge it safer post-credit-crunch particularly out of fear of developers filing for creditor protection or not being capitalised enough to complete existing builds. Off-plan is being shunned as they believe the hazards nowadays frequently outweigh the rewards, making the resale and let market look altogether more appealing within the context of a grim financial environment.
This will no doubt change in the future with the upcoming of the next property cycle. The million-dollar question is of course second-guessing when that will be!
Your guess is as good as mine.
Financing
Most buyers require a mortgage set-up to finance their property purchase. Post-credit-crunch lenders in Spain have been understandably reluctant to finance properties and they have discouraged this activity by non-subtly raising the borrowing fees to all-time highs.
This however changed earlier on this year when Spain’s number one lender by market capitalisation, Bank Santander, decided to spearhead the change by leaving the door ajar on relaxing its mortgage terms. I am confident that, as in the past, smaller lenders will follow the market leader’s example and begin to facilitate credit by offering more competitive and affordable terms to borrowers which will pave the way to a full-blown recovery.
Spanish lenders are risk-averse nowadays so they expect a buyer to come up with a 30 to 40% deposit. This will however likely change in the near future, as credit begins to flow, requiring smaller down payments from borrowers.
I strongly recommend a buyer reads beforehand my mortgage-related articles:
• Spanish Mortgage Loans: An Overview.
• Spanish Mortgage Loans: Beware of Abusive Clauses.
• Mortgage Collar Clauses Revisited (‘Cláusulas Suelo’).
• Lifetime Loans or Reverse Mortgages in Spain Explained.
The Buying Process
The buying process differs between resale and off-plan property. This is explained because in the former the property is readily available, or key-ready, whereas in off-plan it is yet to be built and takes several years as a norm. I will explain separately both procedures as they each have their own particularities with some elements in common.
I. Resale Buying Process
The full buying procedure is explained step-by-step in my article How to Buy Commercial Property in Spain under the section “Profile on the Buying Process”. This three-step procedure applies to all four resale property types outlined below:
• ‘Standard’ urban resale.
• Commercial.
• Rural.
• Distressed.
Please refer to said article for a full account of details as well as useful tips on common pitfalls to avoid on buying resale property. I won’t replicate the information here as it would elongate this article unnecessarily besides duplicating the information.
The first step is to sign a reservation contract or deposit agreement at a real estate agency which is normally non-refundable. This takes the listed property off the market (normally for the next 30 days). I strongly advise a buyer hires a lawyer before he commits to sign a reservation contract. Some of these deposit agreements are standard templates which may be poorly worded and can create serious obligations for a buyer that go against his best interests.
Examples:
a) As a buyer; by creating an obligation to buy. By setting an unrealistic completion date of only six weeks as from the time of signing the reservation contract when this short timeframe may exceed the time needed to set up a mortgage with a lender. This leads to a breach of the contract which may result in heavy losses for a buyer as he may be ‘forced’ to complete (can be compelled legally to do so by the seller’s lawyer). A buyer can be sued for specific performance by the seller compelling him judicially to buy the property.
b) As a seller; by creating an obligation to sell. Should the vendor opt out (because for example they have found a second buyer willing to pay more) they may be forced to pay double the amount of the down payment placed by the first buyer as a reservation deposit. Likewise a seller may be sued by the buyer for specific performance to try and compel a sale.
The above two examples highlight why it’s highly advisable to hire a lawyer from the outset so that he reviews the clauses set forth in the reservation contract carefully before you sign and pledge to anything. Do not act rashly signing away. Let a lawyer carry out the basic legal checks first.
Strictly speaking a First Occupancy Licence (LFO) is unrequired for resales and applies only to new-build or off-plan property. That said, in some parts of Spain, such as Valencia and Catalonia, a LFO is required for resales as an exception to the general rule. Additionally a trend has emerged over the last couple of years with risk-weary lenders demanding a LFO is produced for resales to cover their backs on granting a mortgage loan. Many transactions are being put on hold because of this ‘new’ requirement for resales which used to apply only to off-plan property as explained in the next section below in detail. The reason being is that lawyers must request from the local town hall copies of a LFO which may take several months. In my personal opinion this is absurd as we have gone from one extreme to another; from lenders blissfully ignoring a LFO for off-plan in the boom days to now demand them for every resale which was never their purpose and defeats their logic. It is daft in my view to ask for a LFO on a twenty-year-old property that has all the utilities connected and has no legality problems of any kind. This simply adds an unnecessary new layer of red tape which may contribute to potentially jeopardize resale transactions constituting a deal-breaker in some cases without adding any legal safety to long-standing resales.
The second step will be to sign a Private Purchase Contract (PPC, for short). This step is optional for resales and at times it is merged with the first one for simplicities’ sake. You normally make a down payment of 10% of the property’s value setting a reasonable date for completion (particularly if you require mortgage financing). If movables are being sold along the property it is highly advisable an inventory is added to the PPC. This inventory should be drawn up with great detail to avoid misunderstandings. This inventory will likewise be added to the Title Deed at the Notary Public on completion. It is regarded as a contractual element which binds both parties. If the seller does not include something from within, it will be regarded as a breach of contract.
The third and final step is to pay the balance and complete before a Notary Public. You will require your NIE number and a valid copy of your passport. Your lawyer will ensure that Community of Owners’ fees, utility bills and IBI tax are all up to date. A new owner is held liable for all community fees from the current year he’s buying on a pro rata basis as well as all those dating back three years. This liability is extensive to what is known as ‘derramas‘ or unforeseen community expenses such as painting the building or fixing the lift. Which is why it is very important that at the time of completion your conveyance lawyer attains a certificate from the Community Of Owners signed jointly by the administrator and president stating that all community fees are up to date by the vendor. Should there be any payment outstanding, it goes against the property itself not against the former owner; your lawyer can always practice a retention at completion to offset this outstanding debt.
II. Off-Plan Buying Process
The procedure differs from resale property for the very reason that the property is yet to be built. It also follows a three-step procedure. I strongly advise reading my article Buying Off-Plan Property in Spain for a full list of potential pitfalls associated to this property type. The major differences with resale property are the time elapsed between the stages, which will normally span a couple of years or more, as well as the stage payments.
The first step once you have chosen a development that suits you is to sign a reservation contract at an estate agency. This deposit is non-refundable. The same warnings highlighted above for resale apply here for off-plan.
The second step is to sign a Private Purchase Contract (PPC) and start making a series of stage payments. These stage payments, as a rule of thumb, equate to half of the properties’ sales value. Stage payments (and initial reservation deposit) should be covered by what is known as a bank guarantee.
Bank guarantees are essential and of utmost importance in the event a developer becomes insolvent or fails to complete a development within a reasonable timeframe for whatever reason. They act like safety nets for buyers on all the money paid. You should be able to keep receipts of all the stage payments (including the initial reservation deposit) as the Notary public will require at completion a detailed trail of paperwork that justifies each and every amount paid to the developer to comply with Spain’s anti-money laundering laws. If you happen to wire your funds to Spain using the services of a foreign currency broker (which in my experience saves thousands of euros) make sure they supply you with justification of all the moneys transferred over to a developer. The problem with off-plan is that stage payments are normally carried out years before completion so it is easy to misplace a receipt of one or more payments which may cause serious issues down the line with the Notary at completion who may even refuse point blank to witness a property conveyance unless all anti-money laundering provisions are strictly adhered to.
The third and final step is to complete before a Notary Public and make payment of the balance (remaining 50%). The third stage normally takes a couple of years after signing the PPC depending on how advanced the construction of the property is. I strongly advise to complete only with a Licence of First Occupation (LFO) in place. Completing without a LFO is legal in Spain but highly inadvisable (only justified in qualified exceptions such as a developer teetering on the brink of insolvency). For a full list of the serious legal associated risks on completing without the property attaining a LFO by the Town Hall’s Planning Department I refer to my article Licence of First Occupation. As from the moment a developer attains a LFO he can legally compel you to complete on the property. This is known as ‘forced completion’.
Before you complete it is strongly recommended you carry out what is known as a snagging list which will highlight any construction flaws i.e. mismatched tiles, damp patches, mould growths, leaking faucets, flaked painting, damaged appliances, unsuitable drainage. Normally I would hire a reputable chartered surveyor who will draft a complete report (to British standards) outlining any build defects or problems. I have never come across an off-plan property that doesn’t have one or more defects at least. Your appointed lawyer will then negotiate with the developer that he finishes or completes any pending works even withholding a pre-agreed amount at completion to guarantee the work will be done. Once you complete on a property, and hand over all the money to the developer, your negotiation position is severely undermined. So any outstanding problems should be fixed prior to completion not post-completion.
At completion one must hand over all the bank guarantees to the developer’s legal representative. Bank guarantees are void as from the time the developer attains a LFO from the Town Hall where the new-build is located, well before completion. Up until the issuance of a LFO any community of owner’s fees are the responsibility of the developer. One is held liable for garbage collection tax as from the time the LFO is issued which normally takes place some two years after completion. You can expect however to receive a backdated billed from the Town Hall for the previous two years. The same applies to IBI tax.
I strongly advise you change all locks to the off-plan property you have just acquired, including storage rooms. Many people had copies of these keys during the construction phase. Your legal representative will change all the utilities over to your name. If you have purchased in a development make sure you acquaint yourself with the Community of Owners statutes and bylaws. Some buyers will try to defer completion until the communal facilities (swimming pool, lush tropical gardens, tennis court) or promised amenities (golf club, luxury hotel, private hospital) are finalised. Holding out completion on such grounds cannot be done (successfully) for legal reasons. Please read my litigation article on the matter: 10 Reasons why Your Case Against a Developer may be Thrown out of Court in Spain.
Associated Buying Expenses
As a rule of thumb purchase costs add 10 – 15% over and above the purchase price. In some regions of Spain, particularly in Valencia, this figure may be higher. Please take thorough legal advice to budget your purchase before you commit. You can read my article Taxes on Buying Spanish Property for more details.
Besides paying taxes (explained below), a buyer is bound to pay the following fees:
• Notary fees (for the formalization of the deeds): approx. 0.1 – 2 %
• Land Registry fees (for the inscription of the deeds): approx. 0.1 – 2 %
• Mortgage & Gestoría fees (if finance is required): 1 – 2 %
• Lawyer’s fees: 1 – 2 %
• Estate Agent’s fees: 5 % (these are paid for by the vendor unless agreed otherwise)
Taxation
I will split the explanation between the taxes that are to be paid at completion and those borne post-completion (to be filed on an annual basis). The former (completion) is common to both residents and non-residents alike. The latter (post-completion) differs as explained below.
A. Completion
You can read my in-depth article Taxes on Buying Spanish Property.
Resale: is subject to Property Transfer Tax (or ITP in Spanish) which varies, depending on the Autonomous Community where the property is located, between 7 to 10%. As an exception to this general rule, on buying commercial property, from either a developer or a professional, 21% VAT is applied in lieu of Transfer Tax.
Off-plan: is subject to both VAT (currently set at 10% of the total property price) and Stamp Duty (ranging between 0.5 – 1.5% of the total property price; dependent on location as it varies from one Autonomous Community to the next).
B. Post-Completion: Taxes
You are liable to file and pay Income Tax on owning property in Spain for which you may need to appoint Fiscal Representation in Spain. These taxes differ between buyers holding resident status and those who do not.
i. Resident
Defined as spending in Spain more than 183 days in a calendar year or else have their main centre of interests and activities in Spain (i.e. spouse, children, main business). Residents are taxed on their worldwide income and assets.
ii. Non-Resident
Non-residents are liable for Non-Resident Income Tax and, additionally, may be liable for Wealth Tax on their Spanish assets. You can read further my in-depth article Non-Resident Property Taxes in Spain.
• Resident in E.U. or E.E.A.: 20% (19% as from 2016).
• Non-resident in E.U. or E.E.A. (rest of the world): 24%
Non-EU/EEA residents are taxed at a flat rate of 24 per cent on their Spanish-sourced income – for example, rental income from property in Spain, income from a business in Spain and interest on funds deposited with a Spanish bank. Those who own a Spanish property exclusively for their own personal use and have no other source of taxable income in Spain pay a version of income known as ‘imputed income tax’, which is calculated on the property’s cadastral value (rateable value). Spanish authorities take the view an owner derives a benefit in kind from owning property irrespective of whether it is true or not and taxes it accordingly.
Wealth Tax had been supressed but has recently been reintroduced as a consequence of the financial crisis. Please read my article, in collaboration with Blevins Franks, on Spanish Wealth Tax (Patrimonio) for more details.
Careful with the Tax Office on Buying or Selling at a Discounted Price – La Complementaria
Now that I’ve established it is a great time to buy property in Spain – the bad news. Due to Spain’s ongoing real estate depreciation many buyers are securing properties at such knockdown prices they are unwittingly drawing the attention of the Tax Office. So much so that over the last years many will have received a letter from Spain’s Inland Revenue some six months after completion demanding supplementary tax is paid on the property on having ‘underpaid’ ITP or Property Transfer Tax. This is known as “la complementaria” in Spanish legal jargon and affects resale property. You can read further in my article La Complementaria or Bargain-Hunter Tax on how to pre-empt it and how to appeal one.
This can be explained because the authorities use standard value tables (“bases de comprobación de valores”) to draw a comparison between the fiscal value of the property and the declared sales price at completion. These tables were reviewed every now and then following the upward trend in property price. This was fine so long as there was a continuous capital appreciation but when the market grinded to a halt seven years ago these tables froze in time and do not reflect accurately the overall 50% depreciation real estate assets have undergone (speaking in broad terms). So basically the rateable values that Tax Authorities zealously use are, at best, outdated showing in most cases top-of-the-range pre-crash valuations which are logically not in line with today’s market values.
If the Tax authority detects a statistical meaningful deviation they will exact the difference in what they deemed the buyer has ‘under-declared’. In most instances this is simply not the case. Buyers have only shrewdly taken advantage of the opportunities a crashed real estate market has to offer. Albeit unbeknownst to them this draws the attention of Regional Tax Authorities which will do their best to recoup what they (wrongly) see as an ‘under-declared’ sales price.
On buying distressed Spanish property you should pre-empt this by requesting beforehand an assessed property valuation specifically for tax purposes. This will be a legally binding report which your lawyer may use at a later date.
If you have already received this letter don’t panic, this is happening frequently. You can either pay the requested tax or else appeal it. Providing the difference is not deemed as ‘significant’, your chances of appealing it are fairly high.
If it the amount demanded is low I honestly believe it is not worthwhile the aggravation to appeal. The key decisive factor is that the difference between the fiscal value (the rateable values explained above) and the declared value (what is recorded in the Title Deed at completion before the Notary Public) should be high enough to attract a large tax bill; this will warrant paying a law firm for its legal services. Law firms charge typically between €800 up to €3,000 for this service (this is inclusive of a chartered surveyor’s valuation necessary to appraise the property). So basically any tax bill high enough that exceeds said amounts will easily offset both a lawyer’s and appraiser’s fees warranting an appeal. For high-end property lodging an appeal on a “complementaria” is worth every penny in my professional experience.
Post-Completion: Make Sure Your New Property is registered under Your Name
Once you’ve completed (or closed) on the property before a Notary Public you should ensure it has been registered under your name. A property normally takes two to three months to be registered at the Land Registry post-completion (if no mortgage finance is required).
You will be given the ‘original’ Title deed to the property a few days post-completion. Losing the original Title deed (“Escritura”, in Spanish) is only a minor setback as you can easily request copies from the Notary before it was witnessed.
If you require mortgage financing you will have to sign additionally, besides a Title deed, a Mortgage deed. Your lender will be the one dealing with registering the property; expect at least a six-month delay – if not more – until you are returned the ‘original’ Title deed. Lenders withhold always the original Mortgage deed for their own records and will give you only an authorised copy. Once the property has been duly registered you can request the ‘original’ Title deed for your safekeeping.
The reason why it takes so long is that all taxes associated to the purchase must be paid first. Only then can the deed transferring ownership be lodged at the Land Registry. A buyer can ensure everything is above board on requesting a Nota Simple. I would advise requesting one only after two to three months have elapsed since completion. Law firms can provide you a copy of a Nota Simple translated into English for a reasonable fee.
Post-Completion Checklist
Once you have acquired your new property, you will now have to face all the associated running expenses besides the taxes I already explained in a previous section above. Make sure you have budgeted these expenses carefully so as to avoid unpleasant surprises! Some of the luxury gated communities with lush tropical gardens and beautiful infinity pools that dot the Spanish coastlines have pretty steep maintenance expenses (tallying several hundred euros a month!).
Any unpaid community bills will result in the Community of Owners placing a charge against your property which may lead to auctioning it off publicly to recoup the debt! This legal procedure in Spain works fairly efficiently (as in twelve months on average). Moreover unpaid communal debts can be chased by Spanish Community of Owners abroad against assets you hold in your home country (within the European Union). Please read my articles Bad Debtor’s List (“Fichero de Morosos”) and Spanish Creditors Pursuing Debts Abroad. I also advise hiring home insurance as it is notorious that properties built in Spain are not entirely waterproof (or at least not to the same standards as in the UK) and are prone to damp patches in the winter period.
You should open a Spanish bank account if you haven’t done so already. Utility companies do not accept overseas payments so you should set at least all the following as a direct debit against your Spanish account:
• Utility bills (invoiced quarterly in the case of water and monthly with electricity).
• Rubbish collection tax. Paid twice or once a year depending on the town hall.
• IBI tax. Paid annually (akin to the UK’s Council tax). I strongly urge this tax is set up as a direct debit; failure to pay it may lead the authorities to auction off your property in a procedure which is surprisingly expedient – as in months. Whoever is the owner of a property on the 1st of January of the current year is liable to pay for this tax.
Finally, on owning property, I cannot stress enough how advisable it is that you make a Spanish Will to dispose exclusively of your Spanish estate. This will not preclude any other made in your home country and is limited to your Spanish assets. It will save your beneficiaries time, money and hassle at a time of bereavement.
On a positive note the European Court of Justice on the 3rd of September 2014 has put an end to discrimination between residents and non-residents on benefiting from regional tax allowances regarding Spain’s Inheritance Tax. This landmark ruling will now force the Spanish Government , as it cannot be appealed, to allow non-residents to benefit as well from the generous regional tax allowances which until now were (unfairly) reserved to those holding resident status only. Predictably non-residents will group seeking a refund on what they overpaid over the last four years (statutory time period). This was a contentious point that I had been criticizing for years in all my articles and blog posts on the matter as discrimination cannot be tolerated among fellow EU member states as it undermines the very principles on which a united Europe was built on.
How to Buy Property in Spain – Conclusion
The budding signs of recovery are abundant indicating a turn of the tide in 2014. It is an excellent time to buy property again in Spain taking advantage of today’s post-crash low prices. I must highlight that in the particular case of British the favourable exchange rate trend only makes things cheaper by reducing the average conveyance transaction by thousands if not tens of thousands as the pound is on a two-year high against the euro. Osborne’s bold pension reform also provides new opportunities to seize the moment.
The strengthening of the pound against the euro, record low interest rates and big discounts make three compelling arguments to seize the opportunity and buy now.
Make sure you are assisted on your house-hunting by reputable experts (such as a long-established real estate agency, a reliable mortgage broker or a seasoned lawyer) to benefit most from the wide range of available bargains – you will be spoilt for choice.
I would advise buying with a view to enjoy the property and Spain’s privileged mild weather rather than be on the prowl for a quick profit as I believe that it may still take a while before we see again consistent capital appreciation.
I would also strongly advise that you rent a property in the area you are interested in for a reasonable time before committing to buy just to test the waters and experience first-hand the effect of seasons and how they impact your property and surroundings. You will avoid nightmare scenarios such as buying a flat above a late-night bar that only springs to live in the summertime.
You could always go for a Rent-to-Buy contract which allows you the freedom of letting a property whilst simultaneously entitling you the right to exercise a purchase option if interested (at a pre-agreed heavy discount stipulated in the lease contract which is well below the current market value); a win-win for both landlord and tenant. For more information please read my article Let-to-Buy in Spain: The Smart Choice which explains the pros and cons in detail. Alternatively you may be interested in buying property with a view to rent it out. Please read my articles Letting in Spain: The Safe Way and Tenant Eviction in Spain.
That said if you are buying for the long-term on a well-located area you should do nicely over the next years as an investment provided you purchase now at a reasonable price while bargains are still available.
“You never know what you have until you lose it” – Anonymous.
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in taxation, inheritance, conveyancing, and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
- Conveyancing – Buying
- Conveyancing – Selling
- Rentals
- Fiscal Representation (Non-Resident Income Tax)
- NIE Number (Tax Identification Number)
- Fiscal Representation (Non-Resident Income Tax)
Related articles
- How to Buy Property in Spain – Advice by the Foreign & Commonwealth Office
- Buying Distressed Property in Spain – 8th August 2011
- Community of Owners in Spain: Challenging Assembly Resolutions – 10th October 2011
- Off-Plan Construction Guarantees – 8th November 2011
- Rent-to-Buy in Spain: The Smart Choice – 8th April 2012
- Non-residents: Six Advantages of Making a Spanish Will – 8th August 2012
- Community of Owners, or Comunidad de Propietarios – 8th July 2012
- Buying Resale Property in Spain – 21st February 2013
- Title Deed Explained – 8th April 2013
- Nota Simple Explained – 8th April 2013
- Licence of First Occupation – 8th April 2013
- Bank Guarantees in Spain – 8th April 2013
- Buying Off-Plan Property in Spain – 8th of June 2013
- Investor Guide to Spain’s Golden Visa Law – 8th November 2013
- Bank Repossessions in Spain – 21st February 2014
- Buying and Owning Spanish Property through Companies: Pros and Cons – 7th March 2014
- How to Buy Commercial Property in Spain – 4th July 2014
- How to Buy Rural Property in Spain – 8th August 2014
- How to Buy Property in Spain Safely – 10th October 2014
- Taxes on Selling Spanish Property – 8th December 2014
- Spanish Wills and Probate Law In Light Of European Regulation – 8th January 2015
- Changes to Spain’s Inheritance and Gift Tax Law – 21st February 2015
- Spain’s Holiday Rental Laws – Explaining the Latest Changes – 8th March 2015
- Supreme Court Rulings on Bank Guarantees – 8th April 2015
- La Complementaria or Bargain-Hunter Tax – 8th May 2015
- House Hunting in Spain – The New York Times. June 2015
- Taxes on Buying Spanish Property – 8th July 2015
- Dispelling Spanish Inheritance Tax Myths – 8th August 2015
- Non-Resident Taxes in Spain – 8th December 2015
- Resurgent Spain: Málaga Sees Strong Sales – Mansion Global (The Wall Street Journal). December 2015
- Snagging List Explained – 28th October 2016
- Buying Property in Spain – 10 Reasons to Hire a Lawyer – 8th November 2016
- Buying Property in Spain from a Private Seller (Resale Property) – 21st of February 2017
- Buying Property in Spain from a Developer (Off-Plan Property) – 8th March 2017
- 8 Tips on Buying Off-Plan in Spain – The Address magazine (pages 358 - 373). December 2018
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more

New Driving Laws in Spain
Raymundo Larraín Nesbitt, September, 8. 2014
Most people who own property in Spain need to drive a car here too. Regular legal-contributor Raymundo Larraín Nesbitt strays from his usual property themes to update us on the major novelties in Spain’s new traffic laws.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
8th of September 2014
Photo credit: Daily Mail. © Getty Images.
Introduction
Spain has recently passed new motoring laws which came into force last 9th of May 2014. This new law merits an article unto itself as it significantly alters and impacts existing legislation. I have purposely written it in bullet points so readers can easily skip through the drivel to reach the section they are interested in.
As a disclaimer this article only highlights major changes; it is not to be taken or construed as an exhaustive guide to existing road laws. As a word of caution, this new law only establishes ‘master strokes’; the fine print will be elaborated in detail in future regulation.
This leads me to apologise in advance if some points in my text are obscure. Regrettably the new law leaves quite a few grey areas open to interpretation until further regulation is passed i.e. use of child seats by minors! Not ideal.
Law 6/2014 of 7th of April
The complete wording of the law, in Spanish, can be found in Spain’s Official Law Gazette (B.O.E.). This new law amends Spain’s Highway Code (Law 339/1990).
Major Highlights
1.Speeding
Art 1.10
• Increased in motorways to 130 kph (existing speed limits remain in force however if safety is in doubt)
2. Drink-driving & Drug-driving
Art 1.9 & 1.18
• The legal amount permitted is:
i) 0.5 grams per litre of blood or 0.30 g/l for new or professional drivers.
ii) 0.25 milligrams per litre of exhaled air or 0.15 mg/l for new or professional drivers.
For those – like me – who are still left clueless on the above I put practical examples for both men and women. Alcohol consumption and its effects vary from one person to the next depending on various parameters: age, gender, speed of alcohol consumption, empty stomach, exhaustion level and weight. In general terms for a man weighing 70 kilos this translates to 1.5 beers (understood as half pints in Spain) or two glasses of wine. For a woman weighing 60 kilos this translates to one beer or one and a half glass of wine. So you may want to keep at bay any binge drinking on a Friday night!
• In addition to breath alcohol testing carried out by the Guardia Civil in its random road checks drivers may also be tested for drug-use. If you test positive, besides losing up to six driving points and incurring a hefty fine (detailed below in section seven), you may even lose your driving licence and have the car immobilised. The exception to this rule are medically prescribed drugs. These tests are mandatory and may not be refused without facing legal consequences. Anyone involved in an accident may be forced to take alcohol and drug tests (even pedestrians).
3. Cyclists
Art 1.12 & 1.14
• The use of helmet is mandatory for under sixteen-year-olds.
• The use of helmet is compulsory on cycling on interurban roads and its use is ‘recommended’ on urban roads as well.
• On overtaking cyclists a distance of 1.5 mts must be observed by drivers. If an overtaking maneuver poses “any” danger to a cyclist a driver must desist until it is deemed safe. Again an open-ended criteria that ought to be ruled in detail in my humble opinion to avoid grey areas specifically on affecting people’s life’s (cyclists).
4. Foreign-plated cars
Art 1.16
• Foreign residents: any vehicle owned or driven by them with a foreign licence plate must be changed over to Spanish plates – no exceptions.
• Non-residents: forbidden to circulate in Spain with uninsured foreign-plated cars.
• Non-residents: forbidden to drive in Spain foreign-plated cars which have not passed the equivalent of the Spanish ITV (UK’s MOT).
5. Children
Art 1.17
• Forbidden to drive under twelve-year-olds in motorbikes (as passengers).
• Following Art 1.8 and 1.17 small children, relating to weight and height restrictions (unspecified), may not occupy front or rear seats (sic). Note: Unfortunately the law is unclear on this point and leaves the door ajar to future regulation to elaborate this point in detail. This grey area leaves this article open to interpretation until the regulation is passed. Being a parent this makes me deeply unhappy.
To solve this one must refer to Spain’s 1990 Highway Code (Art 117) and its 2003 regulation as amended by Royal Decree 965/2006.
I construe this as any child under 135 centimetres may not occupy the front seats even if placed on a child seat. They must occupy only rear seats and in addition should be placed on an approved homologated child seat (“Sistema de Retención Infantil” or SRI in Spanish).
Transporting children under 1.35 metres in height (4 feet and 43 inches) regardless of age requires the mandatory use of a child seat . This extends to rent-a-cars and taxis (you must source your own child seat and be able to demonstrate it on renting a vehicle). Professional drivers, such as taxi drivers, will not be held liable on passengers breaching the law. The fine will be €200 and the (private) vehicle maybe immobilized by law enforcement agents. Tourists should pay special attention to this point on passing through or on holidaymaking in Spain.
Children equal to or taller than 135 centimetres may occupy front seats so long as they wear a driving belt.
Dummy-poof recap for concerned parents:
• Minors < 1.35 metres (4 feet and 43 inches) may only occupy rear seats and use of an officially homologated child seat is mandatory.
• Minors ≥ 1.35 metres may occupy front seats (or rear seats) strapped by seat belts.
The use of seat belts is mandatory for all passengers.
6. Radar Detectors
Art 1.17 & 1.18
• The use of such speed-detecting devices is prohibited resulting in fines of up to €200 and you stand to lose up to three driving points.
7. Fines
Art 1.24
• Payment of fines increased to 20 days qualifying to obtain a 50 per cent discount.
• Fines range from €500 to €1,000 for driving at double the amount permitted (Art 1.20). Driving points lost range between four to six points.
• Fines range from €500 to €1,000 for driving under the effects of drugs (Art 1.20). Up to six driving points lost.
8. Penalty Information Exchange between European Driving Agencies
Additional second disposition.
European Driving Agencies will freely exchange information on road penalties relating specifically to:
• Speed-driving (fines).
• Drink-driving.
• Drug-driving.
• Jumping red lights.
• Non-compliance with mandatory use of seat belt.
• Non-compliance with mandatory use of helmet.
• Driving using a mobile or similar handheld devices.
• Driving on the wrong lane, reserved to specific vehicles or unauthorised overtaking.
The following three countries have opted out of the above penalty information exchange scheme: United Kingdom (DVLA), Republic of Ireland and Denmark.
Conclusion
Driving in Spain is fairly different from the UK. And I am not referring to driving on the other lane. As a real-life example after having lived and worked in the United Kingdom for the last four years only once did someone blow the horn at me (and yes, it was justified). On coming on holiday to Spain, in the space of only three days I was honked at no less than five times – all unjustified.
The lesson here is that on travelling abroad you would do well to acquaint yourself with local driving laws and get accustomed, as much as possible, to your new driving ‘idiosyncrasy’; take it from me!
“When in Rome, do as the Romans do” – St Ambrose.
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
How to Buy Rural Property in Spain
Raymundo Larraín Nesbitt, August, 8. 2014
The following article is the fifth, and last, on my five-part series ‘How to Buy Property in Spain Safely‘. You may also be interested in reading Buying Resale in Spain, Buying Off-Plan Property in Spain, Buying Distressed Property in Spain or How to Buy Commercial Property in Spain.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
8th of August 2014
Introduction
Rural property; to many these two words conjure idyllic visions of a bucolic lifestyle in a placid setting silhouetted against a dramatic dusk sky drop. To me they simply mean accident waiting to happen. Call me jaded.
Buying rural land in Spain is unlike anything in the United Kingdom; it is riddled with problems. Beware of anyone telling you the opposite; they are lying through their teeth. It accounts for well over half of the horror stories affecting expatriates we read in the press every now and then. The main reason behind this is that most people do not fully grasp the concept of rural land in Spain which differs from their home country. From this simple misunderstanding stem most of the problems i.e. buying on the wrong assumption you will be allowed to build a new property there.
I simply cannot stress enough the importance of appointing a conveyance lawyer from the outset on buying rural land in Spain. This is the single best advice I can give anyone.
Eight Useful Tips for Buyers of Rural Property in Spain
1. Is the Property Registered under the Vendor’s Name?
This may sound as a fairly obvious point but quite often than not I’ve found out the person who had the property listed at the estate agency was not the registered owner. This can be explained for a number of legitimate reasons i.e. the registered owner has passed away recently and the inheritance tax liability has not been sorted out yet. Until the Spanish IHT is not settled, the property cannot be registered, mortgaged or sold by his beneficiaries.
With rural property in particular it is often place the vendor is not the registered owner (specifically when buying from locals). This is because inland property may be passed several times from one generation to the next without anyone actually bothering to update the change of ownership at the Land Registry. After all, in a small village everyone knows each other and who owns what; so it’s fairly pointless (from their perspective) to lodge the new details. There are several legal ways to overcome this minor setback; such as an ‘Acta de Notoriedad’ or else following an ‘Expediente de Dominio’.
This will likely be the first check your appointed lawyer will carry out. You can actually request a Nota Simple yourself from the Land Registry where the property is located; either physically or online (you have to be a registered user for the latter).
Only the registered owner or else someone appointed by him acting as proxy (through a Power of Attorney) can sell a property.
2. Is the Title Deed Accurate? Moreover, does a Title Deed even exist?
It may come as a surprise, but do not take a Title deed for granted when it comes to rural land. Indeed, Title deeds may not even exist. As a rule-of-thumb I recommend walking away from a rural property that has no Title deed. The legal nightmare you are going to get yourself into is seriously not worth the aggravation.
Should a Title deed exist, it is frequently outdated and inaccurate. The golden rule is not to buy rustic property (in fact any type of property) until a vendor has fully updated all the missing details at the Land Registry (at their expense) to the buyer’s lawyer satisfaction. Unregistered extensions have legal repercussions on seeking finance that one ought to be fully aware of as I explain below in two examples; one from a buyer’s and one from an owner’s perspective.
From a buyer’s perspective that plans to use the rural property as collateral to secure a mortgage loan, let us think of a property which has undergone extensive refurbishment and extensions over the years to the point it is now a villa with a whole new wing plus a swimming pool. When a lender checks the Title deed only a one-bedroom campo house is mentioned with an orange grove; there is no trace of a villa. Consequently a lender will only volunteer a small fraction of the asking price as it considers the new extensions do not exist (legally). This may jeopardise the sale for lack of appropriate funding.
From an owner’s perspective, consider the case of an elderly couple owning rural property of substantial value with multiple unregistered extensions. They seek to improve their lifestyle by requesting a lifetime loan. A lender will examine the deeds of the rural property and will only offer them a mere fraction of what they could have achieved had these extensions been properly registered.
The lesson to be learnt here is that what is not legally registered at the Land Registry is as if it did not legally exist to a lender. For those seeking finance (either as a buyer or as the owner) a lender’s mortgage valuer is obliged by law to reduce the property’s valuation in line with any non-registered features meaning loan seekers stand to receive significantly less than what they would otherwise be entitled to i.e. a rural property with a market value of £500,000 which villa and outbuildings remain legally unregistered would only fetch a value of £100,000 in a lender’s eyes. Bottom line; lodge at the registry all extensions and refurbishments, it’s in your own best interests.
3. Are There Charges, Encumbrances, Liens or Debts Against the Property?
Self-explanatory. Any debts go against the property itself, not against the owner i.e. an outstanding mortgage would be a financial lien against the property. Any debts or charges become the responsibility of the new owner. This is why it is the conveyancer’s duty of care to ensure a Title deed is passed over free and clear of charges, encumbrances and debts. Deed restrictions create limitations or obligations on the property use that a would-be buyer should be made aware of prior to acquiring the land.
Rural property abounds with easements unlike its urban counterpart due to its very nature. Common examples:
• Right-of-way: adjoining plots of land may have a lien to facilitate access to a neighbour’s property. Another example; Shepard’s may have a right (consuetudinary law) to enter your property at certain times of the year to herd their flock (transhumance).
• Hunting rights: your land may subject to cynegetic interests and turned into a hunting ground during the shooting season. Be at the ready to collect all those spent cartridges.
• Right-of-view: this encumbrance caps the building height on the plot of land so as not to impede the views of an adjacent plot.
• Right to extract water: from your private well or from a stream running through your property’s boundaries.
4. Is the Property Lodged Accurately at the Land & Cadastral Registries?
Rural property more often than not is inaccurately described at both the Land Registry and the town hall’s Cadastral Registry. Typical discrepancies include but are not limited to:
• Plot size: frequently real-life measurements differ from what is reflected at both the Land Registry and ‘Catastro’. This is why on my eighth tip, further below, I strongly recommend a chartered Surveyor is commissioned to carry out a surveyor’s report where such discrepancies will come to light. This discrepancy can be explained because land over time may be extended to compromise adjoining plots which are bought or else may be reduced as a result of successive inheritance procedures that divide it. These changes may have gone unrecorded officially.
• Inaccurate property description: as mentioned above in my second tip we can think of extensions or refurbishments made to the property which have gone unregistered by the owners to the point a dwelling’s footprint has been illegally increased.
• Boundaries: rustic properties’ boundaries are hazy at best. Limiting the boundaries of a plot of land using the names of neighbours long deceased is not exactly ideal. This can be highly confusing. Another example is that rural land is frequently demarcated by white boundary stones (‘mojón’) or some iconic landmark (old tree). Needless to say boundary stones can be displaced (heavy rainfall) and a tree can always be chopped down. These blurred lines give rise to interesting legal disputes between adjoining plots of land.
The buyer’s lawyer should ideally insist a vendor corrects and updates the reality so it is reflected legally in both the Land and Cadastral Registries prior to the property being acquired. Any discrepancy will bring about legal and financial consequences such as those I have highlighted above in my second tip regarding seeking finance from a lender using the property as collateral. A buyer’s lawyer can always practice a retention at completion to safeguard the amendments will be carried out by the vendor but ultimately I advise not to complete until they are effectively carried out.
5. Is the Charming Rural Villa Built on the Land Legal? Specific Focus on ‘Casa de Aperos’
I feel compelled to emphasise this point as it affects scores of rural landowners and may in fact lead to criminal prosecution by the state.
Some owners, either out of (inexcusable) ignorance or else purposefully, abuse the planning system using a legal loophole (‘casa de aperos‘) to circumvent planning restrictions to build on rural land. Traditionally Spanish Authorities were lenient in such cases to the point nothing was done for decades. However over the last years the Government has taken a firm stance clamping down on all who build on rural land earmarked as unfit for development.
The most common example is when an owner of rural property applied for a licence to build a tool shed (‘casa de aperos’) of 3*3 m² to store the tools to plough the fields. The landowner purposely exploits this legal ‘loophole’ to circumvent planning limitations and build a rustic villa instead. The reason a landowner would breach planning laws and risk prosecution is because a rural plot of land stands to appreciate significantly on building a villa.
This may lead local authorities to threaten with a demolition order, at the owner’s expense, besides imposing heavy fines and even face prosecution in the most serious cases. Almost every case we read on the newspapers of British having their rural property under threat of looming demolition relates to what I have just explained.
A buyer’s lawyer will determine if a rustic villa does have planning permission from the local town hall. If it doesn’t, then I strongly recommend a buyer walks away from it to avoid a legal quagmire. Beware of all those rural properties advertised “with planning permission”. Most are ‘web bait’.
6. Does the Property Comply with both Town Hall and Regional Planning Regulations?
This carries on from the previous point. It is essential your conveyance lawyer ensures the rural property complies with both local and regional planning authorities.
Remember the Prior’s? The impact on people’s lives on having two administrations squabbling over planning competencies simply cannot be understated. This is a real-life example on how a British couple’s dream to live a placid retirement inland was shattered. The Prior’s applied for a Building Licence at their local town hall’s planning department which was subsequently issued. Relying on its validity they went on to build a villa on their rural land; so far, so good. However, unbeknown to them the BL was challenged administratively by a third-party. This led to an ongoing dispute between the town hall and the Regional Planning Authorities over the legality of the issued BL. Regional Authorities are empowered to override planning decisions made by hierarchically lower administrations, such as a town hall, so they are bound to win. As a result their dream villa was demolished – at their cost.
Another example of the importance of double-checking everything is above board on planning issues is Valencia’s Land Grab Law. Admittedly this is a problem that only affects one of Spain’s seventeen Autonomous Communities but the international (negative) media repercussion it’s had has been huge.
7. Is the Property Connected to the Mains? Does it have Access to its own Running Water Supply & Utilities?
Spain is not a “dust bowl” (as one of my London friends enjoys teasing me). Spain’s climatology is diverse as it’s affected by both the Atlantic Ocean and the Mediterranean Sea. As a result north and north-west Spain has a cold and wet climate with heavy rainfall comparable to the UK. Whereas south and south-east Spain enjoys a privileged warm weather all year round. The practical impact this climatic diversity has on rural property cannot be underrated.
Whilst water may not be an issue in the north, southern Spain is a whole different story. It often suffers from severe bouts of draught lasting several months. Local Authorities will enforce severe water restrictions. Water shortage coupled with sweltering heat is a lethal combination that will kill off any tree or plant in your property. Rural landowners have devised countermeasures over time to offset draught’s effects such as digging up their own wells to secure access to water. However even such wells dry up from time to time as was the case of my clients who were baffled because they had basically been cut off from their water supply and were very much isolated in their campo house in the middle of nowhere.
A surveyor’s report will highlight for example if the property is connected to the mains drainage. Frequently rural properties are not connected to the mains sewarage and have their own septic tanks in use which leads to problems as these must be emptied every now and then to avoid ‘overflow’ and ‘seepage’ problems, not to mention health-related issues.
Additionally few rural properties are connected to the electric grid. It is very important a would-be owner fully understands what utility connections are available – if at all – and its limitations i.e. power surges. It is commonplace rural properties have their own generators which bears severe restrictions on the use of household appliances.
8. Hire a Chartered Surveyor
I have badgered relentlessly over the previous seven points, with practical examples, on the usefulness of hiring a surveyor. In my opinion it should be mandatory when it comes to purchasing rural property (in fact, any kind of property). The cost of a valuation survey will be largely offset by the problems that are picked up by a seasoned professional. This valuable report can be then used by a lawyer to know what weak points to watch out for and which are likely to give problems down the line. The lawyer will then use this insight to his client’s advantage knowing what should be negotiated and worded into a Private Purchase Contract, prior to completion, to better protect the buyer’s interests. Bear in mind that conveyance lawyers, under normal circumstances, do not visit properties; we only examine the associated legal paperwork.
Taxation
From a buyer’s perspective, rural property is subject to Property Transfer Tax (ITP) which varies, depending on the Autonomous Community where the property is located, between 7 to 10%. Rural property is a speciality of how to buy resale property.
Post-Completion Checklist
A property normally takes two to three months to be registered at the Land Registry. The reason being is that all taxes associated to the purchase must be paid first. Only then can the deed transferring ownership be lodged at the Land Registry. A buyer can ensure everything is above board on requesting a Nota Simple. I would advise requesting one only after three months have elapsed since completion.
You should open a Spanish bank account if you haven’t done so already. Utility companies do not accept overseas payments and like setting invoices as standing orders against your Spanish account. You should set at least as standing orders all the following:
• IBI tax. Paid annually (akin to the UK’s Council tax).
• Garbage collection. Paid twice or once a year depending on the town hall.
• Utility bills (invoiced quarterly in the case of water and monthly with electricity) if applicable.
You are also liable to file Income Tax on owning property in Spain every year for which you may need to appoint Fiscal Representation in Spain.
Finally, on owning property, I cannot stress enough how advisable it is that you make a Spanish will to dispose of your Spanish estate. This will not preclude any other made in your home country and is limited exclusively to your Spanish assets. It will save your beneficiaries time, money and hassle at a time of bereavement.
How to Buy Rural Property in Spain – Conclusion
Buying rural land in Spain is normally fraught with problems; there is no other way around it. You really need to take on board a good conveyance lawyer from the outset to help you through. Good luck! You are going to need it.
“So, does that mean we can’t use our well?” Client on realising the two-thousand-year-old Roman well on his newly-acquired rural property dried up about the time Carthage was taken over during the Third Punic War (animus iocandi).
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in conveyancing, taxation, inheritance, and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
- Conveyancing – Buying
- Conveyancing – Selling
- Rentals
- Fiscal Representation (Non-Resident Income Tax)
- NIE Number (Tax Identification Number)
- Land Registry Search (Nota Simple)
Related articles
- How to Buy Property in Spain – Advice by the Foreign & Commonwealth Office
- Buying Distressed Property in Spain – 8th August 2011
- Community of Owners in Spain: Challenging Assembly Resolutions – 10th October 2011
- Off-Plan Construction Guarantees – 8th November 2011
- Rent-to-Buy in Spain: The Smart Choice – 8th April 2012
- Non-residents: Six Advantages of Making a Spanish Will – 8th August 2012
- Community of Owners, or Comunidad de Propietarios – 8th July 2012
- Buying Resale Property in Spain – 21st February 2013
- Title Deed Explained – 8th April 2013
- Nota Simple Explained – 8th April 2013
- Licence of First Occupation – 8th April 2013
- Bank Guarantees in Spain – 8th April 2013
- Buying Off-Plan Property in Spain – 8th of June 2013
- Investor Guide to Spain’s Golden Visa Law – 8th November 2013
- Bank Repossessions in Spain – 21st February 2014
- Buying and Owning Spanish Property through Companies: Pros and Cons – 7th March 2014
- How to Buy Commercial Property in Spain – 4th July 2014
- How to Buy Rural Property in Spain – 8th August 2014
- How to Buy Property in Spain Safely – 10th October 2014
- Taxes on Selling Spanish Property – 8th December 2014
- Spanish Wills and Probate Law In Light Of European Regulation – 8th January 2015
- Changes to Spain’s Inheritance and Gift Tax Law – 21st February 2015
- Spain’s Holiday Rental Laws – Explaining the Latest Changes – 8th March 2015
- Supreme Court Rulings on Bank Guarantees – 8th April 2015
- La Complementaria or Bargain-Hunter Tax – 8th May 2015
- House Hunting in Spain – Interview with The New York Times. June 2015
- Taxes on Buying Spanish Property – 8th July 2015
- Dispelling Spanish Inheritance Tax Myths – 8th August 2015
- Non-Resident Taxes in Spain – 8th December 2015
- Resurgent Spain: Málaga Sees Strong Sales – Interview with Mansion Global (The Wall Street Journal). December 2015
- Snagging List Explained – 28th October 2016
- Buying Property in Spain – 10 Reasons to Hire a Lawyer – 8th November 2016
- Buying Property in Spain from a Private Seller (Resale Property) – 21st of February 2017
- Buying Property in Spain from a Developer (Off-Plan Property) – 8th March 2017
- How to inspect an off-plan property overseas – Q&A with The Sunday Times. July 2017
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
How to Buy Commercial Property in Spain
Raymundo Larraín Nesbitt, July, 4. 2014
The following article is the fourth on my five-part series ‘How to Buy Property in Spain Safely‘. You may also be interested in reading Buying Resale in Spain, Buying Off-Plan Property in Spain, Buying Distressed Property in Spain or How to Buy Rural Property in Spain.
By Raymundo Larraín Nesbitt
Director of Larraín Nesbitt Lawyers
4th of July 2014
Resale Similarities
Commercial properties share multiple common aspects on what I had already written on How to Buy Resale Property in Spain. In fact this whole article may be regarded as redundant but just for completion’s sake I’ve decided to go ahead and write it anyway. Most of the points raised for resale property hold true and can likewise be applied to commercial properties. After all commercial properties branch out from resale property and are but a part of it (same rings true for rural property).
Commercial Singularities
Due to the legal business nature of commercial premises a few nuances are introduced (specifically on taxation, opening licence and holding deposit) that a businessperson should be aware of as opposed to standard private property (resales).
Buyer’s Preliminary Checklist
This will be carried out routinely by the conveyance lawyer you appoint. The following list is open-ended and by no means exclusive:
- Is the property under the vendor’s name?
- Is it under a company’s name? A Due Diligence may be required
- Does the vendor have the faculties (i.e. power of attorney) to sell on the property?
- Is the vendor’s Title deed clean? Are there charges, encumbrances, liens or debts against the property? Specific focus on judicial embargoes against the property. If there are any one can negotiate the vendor cancels them prior to completion or even deduct money at completion stage to secure these are effectively removed
- Verify the property’s Planning status with the local town hall. Is if fit for commercial use?
- Check that local taxes (IBI) are up-to-date
- Cross-check the cadastral record for inconsistencies
- Check the Community of Owners’ fees are up-to-date
- Check utilities are up-to-date
Examples of Commercial Property
- This includes storage rooms (trastero) and car parks (plaza de garaje) sold individually and legally separate from a dwelling.
- Commercial premises.
PROFILE ON THE BUYING PROCESS
The buying process can be outlined in three steps. A buyer can skip the first two stages and jump straight to completion.
Stage 1: Deposit Agreement (“Señal”)
You will be expected to pay an initial deposit to strike the property off the market. The amount typically ranges from €3,000 to €6,000. This is normally paid to the estate agency and accounts towards the final sales price of the property. Until you pay this initial deposit an estate agency is free to offer it to anyone else.
A reservation contract is very short, spanning normally only a couple of paragraphs at most, and should ideally outline the following bullet points briefly:
• Vendor’s details
• Succinct property description
• Price
The initial reservation fee is normally non-refundable. This reservation contract offers little to no legal protection as it’s very vague. This is why I strongly recommend you appoint a lawyer prior to signing and handing over the initial deposit. A lawyer will be able to carry out a minimum due diligence on the Title Deed before you pay the non-refundable deposit. Moreover, a lawyer can add protective clauses at this preliminary stage such as “subject to finance being granted”. This clause, for example, helps to offset the potential risk of forfeiting this deposit should finance be unattainable at a later stage. Securing finance from lenders should not be taken for granted in today’s market.
Stage 2: Exchange of Private Purchase Contracts (“Contrato Privado de Compraventa”)
The PPC or preliminary agreement reflects and collates all that’s been negotiated by the parties in detail prior to completion. Completion before a Notary Public will in fact be a mere transcript of what’s been agreed at this key stage. It should state amongst other things:
• Buyer’s details
• Vendor’s details
• Full property description
• Legal status of property
• Holding deposit or option to buy agreement
• Agreed price and its breakdown (stage payments)
• Expected completion date
Either a holding deposit or an option to buy can be agreed upon at this stage:
1. Holding Deposit. Normally amounts to 10% of the property’s asking price (this percentage varies hinging on the foreseen length of time to complete as well as other factors). This deposit is normally non-refundable. You may want to think carefully before committing yourself to sign on a PPC’s dotted line.
There is absolute freedom on deciding how to negotiate and draft such clauses. Bottom line, one should avoid acting rashly and must carefully take the time to decide on what’s been negotiated prior to handing over the deposit.
To put an example of what a lawyer can do for a buyer at this stage. In the case where a buyer relies on finance to close a deal a lawyer can add a clause whereby if the buyer fails to secure mortgage finance the withholding 10% deposit is refunded in full. Think for example of substantial commercial property (in the millions) on a high street in Madrid or Barcelona. The inclusion of such a clause could save a buyer several hundred thousand euros if the deal falls through for lack of finance.
A holding deposit usually takes two different forms depending on what’s agreed:
• “Arras confirmatorias”: The 10% down payment accounts towards the sales price and is deducted at completion. If a buyer decides to rescind the agreement he forfeits the down payment. A buyer has no right to claim it back. Likewise a vendor opting out will be forced to handover a sum of money equating to the deposit. This deposit is deducted in full at completion and forms part of the price.
• “Arras penitienciales”: the 10% down payment is likewise deducted from the sales price at completion. If the buyer opts out he forfeits the down payment in full. However should the vendor opt out he will be forced to pay double the holding deposit. This clause is applied restrictively and obviously benefits a buyer more than a vendor.
I strongly advise (understatement) that this money is paid only into a reputable law firm’s account (usually the vendor’s law firm). This will not technically be an escrow account, unlike in the United Kingdom, but nonetheless lawyers are legally bound to withhold the amounts safely until completion (at no extra cost to the parties).
2. Option to Buy Agreement: a buyer may be interested in having an option to buy the property. The option normally equates to 10 or 15% of the agreed sales price and only sets obligations for the vendor. A vendor, on agreeing, commits himself to sell the property within a pre-agreed time frame to the buyer. If the buyer exercises his option it is deducted from the sales figure at completion. Should the buyer decide not to go ahead with the purchase and exercise his option he forfeits in full the down payment he made.
Stage 3: Completion (“Escritura”)
The third and final phase is to complete before a Notary Public. The two previous steps have set the stage leading to this crucial moment. Once a Public Deed of sale – Escritura in Spanish – is signed, the buyer is given a copy of the Title deed to the property (“Escritura Pública de Compraventa”). All associated taxes (i.e. Stamp Duty, Transfer Tax and VAT) need to be paid first before being able to register a property. This goes to explain why a property takes several months to be registered. Post-completion the buyer’s lawyer will lodge the Title Deed at the Land Registry. Registration grants protection erga omnes (against third parties); the strongest type of public protection available.
Taxation
Spain is divided administratively into seventeen Autonomous Communities. The state has empowered communities by devolving tax competencies. Devolution implies communities hold full competence to rule on certain tax aspects and accounts for regional tax variations from one Autonomous Community to the next. Listing exhaustively all possible tax permutations in minutiae relating to Spain’s seventeen communities blatantly exceeds the goal of a divulgative article which is why I purposely keep it clean and simple and adopt a holistic approach. As a word of caution, sound legal and financial advice should be sought to obtain a tailored breakdown of all taxes (and expenses) incurred by a buyer given their own personal circumstances. The following is a simplification of the tax liability borne by a buyer on acquiring commercial property.
| Tax | Buying from Private Individual | Buying from Developer or Professional |
|---|---|---|
| Property Transfer Tax (ITP) | 7 – 10 % | |
| VAT (IVA) | 21 % | |
| Stamp Duty (AJD) | 0.5 – 1.5 % |
Additionally Plusvalía tax (municipal tax on the increase of value of the land) may be paid by a buyer. The law stipulates it’s the vendor that pays for it but it is commonplace to agree a buyer pays it.
Associated Buying Expenses
Besides paying the above taxes, a buyer is bound to pay the following fees:
• Notary fees: 0.1 – 2 %
• Land Registry fees: 0.1 – 2 %
• Lawyer’s fees: 1 – 2 %
• Gestoría fees (optional): 0.5 – 1 %
• Mortgage fees (optional): 1 – 2 %
Post-Completion Checklist
A property normally takes two to three months to be registered at the Land Registry. A buyer can ensure everything is above board on requesting a Nota Simple. I would advise requesting one only after three months have elapsed since completion.
You should open a Spanish bank account if you haven’t done so already. Utility companies do not accept overseas payments and like setting invoices as standing orders against your Spanish account. You should set at least as standing orders all the following:
• IBI tax set-up. Paid annually (akin to the UK’s Council tax)
• Garbage collection. Paid twice or once a year depending on the Town Hall
• Utility bills (invoiced quarterly in the case of water and monthly with electricity)
• Community fees (only if you’ve purchased in a Community of Owners). Usually quarterly but can vary
You are also liable to file Income tax on owning property in Spain every year for which you may need to appoint Fiscal Representation in Spain.
Finally, on owning property, I cannot stress enough how advisable it is that you make a Spanish Will to dispose of your Spanish estate. This will not preclude any other made in your home country and is limited exclusively to your Spanish assets. It will save your beneficiaries time, money and hassle at a time of bereavement.
Conclusion on How to Buy Commercial Property in Spain
Commercial, Rural and Distressed property are all but specialities of buying Resale property in Spain. I write separate articles on all four because each one sports its own unique nuances which I reckon ought to be fully dissected and explained. I regard Off-Plan property as a different animal altogether that requires its own space as it introduces multiple unique key concepts which are not shared by its resale cousins.
Hiring a reputable lawyer is highly advisable to ensure, as much as possible, a smooth conveyance procedure. Property purchase can quickly turn into a minefield without someone qualified to guide you through the pitfalls safely.
“It often requires more courage to dare to do right than to fear to do wrong.” – Abraham Lincoln
American 16th US President (1809 – 1865). From an impoverished humble background of corn farmers, this self-taught American lawyer, strategist and politician would rise to serve as the 16th US President. He resolutely ensured a pro-Union victory, strengthened the federal government, modernized the economy, brought about the emancipation of slaves and preserved the Union. During his tenure, he held presidential elections in 1864 to be re-elected, amid a devastating Civil War that threatened to tear his country apart and engulf it in a sea of darkness; yet he gave example in the face of adversity, holding steadfast to his ideals, steering the ship safely into port and acting as a beacon of Democracy which light shone with a fierce intensity the likes of which the world has never witnessed, since or after. Never again would a country hold presidential elections amidst a bloody civil war in what constitutes one of History’s greatest democratic feats to date. But most importantly, he went into great lengths to ensure the festering wounds left open during the fratricidal Civil War were healed; generously reconciling both sides in equal terms, as one nation, indivisible, under God. It is for this very reason, that more than two centuries on, he is widely regarded as the greatest American president to grace the White House; likely the greatest American of all time, towering above the rest. Through his courage and sacrifice, which ultimately would claim his own life, he laid the groundwork of what was to become the greatest and most powerful nation on earth over the next two centuries. A true statesman that would always put ahead of any consideration the best interests of his people, by tearing down divisive walls and fostering at every opportunity union.
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in taxation, inheritance, conveyancing, and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
- Conveyancing – Buying
- Conveyancing – Selling
- Rentals
- Fiscal Representation (Non-Resident Income Tax)
- NIE Number (Tax Identification Number)
- Land Registry Search (Nota Simple)
Related articles
- How to Buy Property in Spain – Advice by the Foreign & Commonwealth Office
- Buying Distressed Property in Spain – 8th August 2011
- Buying Resale Property in Spain – 21st February 2013
- Escritura – Title Deeds FAQ – 8th June 2013
- Nota Simple: What is it and how do you get one? – 8th June 2013
- Buying Off-Plan Property in Spain – 8th of June 2013
- Investor Guide to Spain’s Golden Visa Law – 8th November 2013
- Bank Repossessions in Spain – 21st February 2014
- Buying and Owning Spanish Property through Companies: Pros and Cons – 7th March 2014
- How to Buy Rural Property in Spain – 8th August 2014
- How to Buy Property in Spain Safely – 10th October 2014
- Taxes on Selling Spanish Property – 8th December 2014
- La Complementaria or Bargain Hunter Tax – 8th May 2015
- House Hunting in Spain – The New York Times. June 2015
- Taxes on Buying Spanish Property– 8th July 2015
- Dispelling Spanish Inheritance Tax Myths – 8th August 2015
- Resurgent Spain: Málaga Sees Strong Sales – Mansion Global (The Wall Street Journal). December 2015
- Non-Resident Taxes in Spain – 8th December 2015
- Buying Property in Spain – 10 Reasons to Hire a Lawyer – 8th November 2016
- Buying Property in Spain from a Private Seller (Resale Property) – 21st of February 2017
- Buying Property in Spain from a Developer (Off-Plan Property) – 8th March 2017
- 10 Questions you Should Ask your Agent on Leasing Office Space in Spain – 24th May 2017
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarising, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more

Tenant Eviction in Spain
Raymundo Larraín Nesbitt, June, 8. 2014
What do you do if your tenants stop paying the rent? Regular contributor Raymundo Larraín Nesbitt gives a sweeping legal overview on evicting tenants in Spain, emphasising the pro-landlord change of trend in recent court rulings and legislation.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
8th of June 2014
Original article from December 2.007
Introduction
Spanish judges are increasingly ruling more and more pro-landlord. More significantly, the introduction of new game-changing laws, such as Law 4/2013 of Measures to Increase the Flexibility and Foster the Rental Market described further below, have supplied the legal tools with which to bolster the defense of landlord’s interests.
It has finally dawned on the Government, and society at large, that steps needed to be taken to ensure and protect landlord’s interests so as to foster a dynamic letting’s market. As I have extensively covered in previous articles over the last decade, Spain’s rental market is chronically sluggish in stark contrast to fellow European countries which boast a booming mature letting market for all the right reasons (i.e. The United Kingdom). I like quoting the statistic that only 17% of Spain’s properties are rented as opposed to the European Union’s 30% on average. This figure clearly shows better than any other Spain’s national obsession with property ownership ranking only second to football; and frankly I’m not entirely sure on the latter.
Landlords are understandably reluctant to rent out properties in fear of Spain’s clumsy and protracted eviction laws that place tenants at the heart of their interests neglecting the former. This may have been amply justified fifty years ago when tenants were indeed the weak link in a torn society coming to terms with itself after a crude civil war, but this doesn’t hold up a candle in today’s world.
Protecting Landlords
Make no mistake, landlords are the weak link when it comes to rental in Spain; they are by a long shot the ones needing all the legal protection they can muster in today’s deceptive world. Non-paying tenants cause severe consequences to landlords which may even lead to a bank repossession as many are reliant on the rental to cover the mortgage instalments.
Broadly speaking landlord protection can be achieved twofold; both privately and publicly.
Privately, it requires the landlord to proactively adopt a series of measures to bolster and reassert his rights. This is covered in the below section “Renting in Spain Successfully”.
Publicly, it requires a concerted effort from all government institutions and factual powers to make it happen. This is covered in the below section “Tenancy Legal Framework”.
A lawyer can help a landlord on both counts.
A. Renting in Spain Successfully
Without going into detail a landlord may adopt the following measures, abetted by a lawyer, to pre-empt letting problems (chiefly non-paying tenants):
- Tenant vetting. Prospective candidates ought to be carefully screened to weed out unsuitable profiles. Haphazard screening can only spell future problems
- Arbitrage Clause
- Rental Insurance
- Rental Bank Guarantee
- Lodging the Tenancy Agreement at the Land Registry
The above-listed tips are already elaborated in detail in a specific article I wrote on the matter: Letting in Spain: The Safe Way. On pro-actively following these simple pointers, dictated mainly by common sense, a landlord ensures himself a sharp increase in the chances of successfully renting out his property hassle-free.
B. Tenancy Legal Framework
Urban Rental laws compromise a general backbone, constituted by Law 29/1994 or LAU for short, which in turn is constantly being fleshed out by newer laws. These new stream of laws introduce significant nuances to the point of changing the rules of engagement.
1. Law 29/1994, of 24th November
Spain’s Tenancy Act, or LAU, lays out the general legal framework for all rental contracts in Spain drafted after the first of January 1995. This law sets out the legal obligations for both landlord and tenant. The law is skewed towards tenants but less so than the laws it superseded.
2. New Laws
The Government has finally smelled the coffee and has been busy enacting batch after batch of new laws to bolster and uphold landlord’s rights since the ‘recession’ began in 2008. The initial set of laws proved reasonably ineffective in practice as they constituted half-hearted attempts which barely dented the existing status quo. The Government probably thought optimistically it would be a short-lived recession and the changes were more of a cosmetic nature geared towards making the headlines and wooing a growing discontent electorate than attempting to make a real change. However as the recession persistently endured over time, biting deeper into society’s core, it soon became evident that more decisive laws were required. And so newer laws proved to be more adept at streamlining eviction proceedings; resolutely addressing key issues which had traditionally held back fast proceedings. On average a tenant eviction is still taking three to nine months depending on how clogged a law court is.
The change in trend is evident, both from a technical point of view as well as by the unprecedented interest shown in the defense of landlord’s interests. The Government seeks in the protection of landlords a means to an end. By protecting landlords it seeks to foster a healthy rental market. The underlying logic is to gently nudge undecided property owners sitting on the fence and make them feel safer so they will be increasingly tempted to take a dip and become landlords.
The huge demand for housing (at an affordable price), besides a chronically sluggish rental market, goes a long way to explain the Government’s newfound interest in passing new laws that boldly attempt to address the matter for the first time by – ironically – protecting landlords as they hold the key (excuse the pun) to kick-start a more robust rental market. Although Spain currently has an oversupply of property it is not priced correctly to meet the huge latent demand for both rental and acquisition.
Examples of such new national laws are:
- Law 19/2009 of Measures to Foster and Streamline Rental Proceedings
- Law 37/2011 of Measures to Expedite Eviction Proceedings (so-called “Express Eviction Law”)
- Law 4/2013 of Measures to Increase the Flexibility and Foster the Rental Market
The last bullet point, Law 4/2013, epitomises like none other the change in trend on how landlord’s problems are perceived by public institutions. This landmark law was purposefully devised and enacted to counter Spain’s chronically languishing rental market enabling the means to help it become dynamic in line with other more mature fellow European countries’. It introduces a bevy of legal novelties all of which can be read in detail in my article New Measures to Bolster Spain’s Ailing Rental Market, from the 30th of June 2013. Only time will tell if it achieved, or not, its self-declared goal.
New legislation, both national and regional, is increasingly becoming more proficient at tackling the real issues at hand that traditionally plagued landlords (i.e. protracted eviction proceedings). These have held back for far too long the development of a more mature rental market in Spain. This new wave of laws is setting the benchmark by making renting altogether safer, for both residents and non-residents alike, paving the way for a more vigorous and healthy letting market.
Landlord’s Not-To-Do List
Disgruntled landlords should at no time attempt to follow any of the below in Spain least the want to be remanded into custody and be the subject of criminal proceedings instigated by their own tenants. Besides, on following the below a landlord substantially weakens his own legal position in the event of an eviction procedure.
1. Shut-off utilities (water & electricity). Landlords often feel the urge of doing this on their tenant falling in arrears. Your tenant can report you to the police on shutting off the utilities. This may be labelled as either coercion or harassment or both. Your tenant can prosecute you criminally on doing this. So you may want to think twice before doing it. If the utilities are in the name of the landlord, and he stops paying them on purpose to mount pressure on a non-paying tenant, he can equally be prosecuted as it’s legally equated to the physical shut-off of utilities. The landlord will be forced to pay for all the expenses associated to reconnecting his property to the utility service (several hundred pounds) as well as paying the belated invoices and delay interests. For all the reasons outlined, this is not a recommended option. Moreover, it may expose a landlord to be included in a Debtor’s List (“Fichero de Morosos”).
2. Changing the locks or locking a tenant out. Same as above, it may be regarded as either coercion or harassment or both and you may be prosecuted for this.
3. Non-sanctioned tenant eviction. Landlords may feel tempted to take justice into their own hands and break-in their own property assisted by a square-jawed six-foot acquaintance as back-up. This is seldom a bright idea and may land you and your ‘friend’ in a Spanish jail for unlawful entry (trespassing). The only – legal – way to evict a non-paying tenant is to hire a lawyer and initiate a formal eviction procedure through a Spanish law court. New laws have been enacted to help speed up the eviction procedure i.e. Express Eviction law.
4. Entering a property on a ‘routine’ inspection. Although it may be highly tempting to take a quick peak from time to time, especially after a noisy summer party that kept the whole neighbourhood up until the wee hours of the morning, it is hardly a good idea. Landlords often cannot stand the fact they are forbidden from accessing their own property in Spain if it’s not without the prior – written – permission of their tenant. You simply need their permission, following Spain’s Tenancy Act, regardless if they are up-to-date or not with their let.
5. Throwing tenants’ possessions away or threatening them. Self-explanatory.
Conclusion to Evicting Tenants in Spain
The tide has finally turned in favour of landlords. After having spent years criticising how reactive laws and public institutions were in general towards the growing problem of non-paying tenants (specifically post-credit-crunch) the trend is clearly changing now. Landmark reforms such as 2013’s law are resolutely paving the way to streamline eviction procedures. Judges are now more receptive towards landlord’s plights and are taking a clearer stance defending them. Let us hope this marks the inflection point from which a new, more robust, rental market emerges in Spain.
To close, a lawyer can support you twofold; by both assisting you to pre-empt most tenancy issues as well as to oversee a tenant eviction procedure.
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in taxation, inheritance, conveyancing, and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
Related articles
- Rent-to-Buy in Spain: The Smart Choice – 8th of April 2011
- Renting in Spain: Top 10 Mistakes – 8th of June 2011
- Letting in Spain: The Safe Way – 8th of October 2012
- New Measures to Bolster Spain’s Ailing Rental Market – 8th of July 2013
- Bad Debtor’s List (“Fichero de Morosos”) – 8th of April 2014
- Spanish Creditors Pursuing Debts Abroad – 8th of May 2014
- Tenant Eviction in Spain – 8th of June 2014
- Holiday Rental Laws in Spain – 8th of March 2015
- Non-Resident Taxes in Spain – 8th December 2015
- Holiday Rental Laws in Andalusia (Decree 28/2016) – 8th of February 2016
- Decree 20/2002: Andalusia’s Holiday Rural Rental Decree – 8th of April 2016
- Urban Rental Law in Spain – Spain’s Tenancy Act (Ley de Arrendamientos Urbanos, LAU) – 8th of May 2016
- Energy Performance Certificate – 7th of November 2016
- Renting in Spain - Landlord´s Taxation – 8th of January 2017
- Renting in Spain: Non-Resident Landlord's Rental Reliefs – 14th of January 2017
- 10 Questions you Should Ask your Agent on Leasing Office Space in Spain – 24th May 2017
- Holiday Rental Home Taxation in Spain – 8th of July 2017
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarising, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.007 and 2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
Spanish Creditors Pursuing Debts Abroad
Raymundo Larraín Nesbitt, May, 8. 2014
Spanish lenders are getting better at pursuing debts across European borders. Solicitor Raymundo Larraín Nesbitt gives a legal overview on how rulings from EU Member States can be enforced in other Member States on civil and commercial matters following either a European Enforcement Order (EEO) or Council Regulation EC No. 44/2001.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
8th of May 2014
The European Enforcement Order (EEO) and Recognition and Execution of EU Member State Rulings (EC No. 44/2001)
I am always surprised by comments made by European non-residents regarding their sense of impunity on defaulting, for example, a Spanish mortgage loan agreement. Some debtors harbour the impression that Spanish creditors either cannot pursue their home countries’ assets or else that they will lack the necessary commitment to allocate resources and time to the task. Whilst this may be true in some cases (small amounts owed) the truth is that this is a serious error of judgement which may come back to haunt them for the remainder of their life. This blunder may stem from their lack of knowledge on how European legislation and its implementation work out in practice.
After the rampant property folly of the past decade, fueled by ultra-low interest rates and easy credit, it comes as no surprise that thousands of borrowers are struggling to make ends meet in Spain or even find themselves trapped in negative equity with Spanish real estate. This situation has been aggravated compounded by the strengthening of the Euro against other currencies (Sterling Pound), high levels of unemployment, 2008’s financial meltdown, post-credit-crunch (liquidity shortage; the lowest on record on a fifty-year period), falling property prices across the board and finally amid sovereign-debt concerns.
Scores of non-residents have been unwittingly caught by the above negative scenario in Spain and have decided to flee the country so as not to face their financial commitments. As a result they may now find their home assets jeopardised (even their main abode) under the threat of Spanish creditors actively pursuing debts abroad using European legislation.
Having in mind specifically British and Irish nationals, I’ve written this short article to explain just how a legal matter arising in Spain may affect you and your family’s assets back home. Examples of such are:
• Defaulting on mortgage loan instalments on a second home in Spain.
• Falling in arrears with your Community of Owners.
• Outstanding amounts owed to developers on buying off-plan property (forced completion).
• Unpaid personal loans.
• Pursuing negative equity abroad: post-auction shortfall on Spanish bank repossessed property.
I must add that recent Spanish lower court rulings (not legally binding) are increasingly reluctant to the idea of pursuing borrowers for negative equity following a social outcry on grounds of the unfairness of an alleged rigged procedural system biased towards lenders. Should this trend catch on by higher courts and become consolidated it may eventually put an end to pursuing negative equity abroad. In the interim UK courts may take into account these low court Spanish rulings on deciding whether or not to refuse an EEO in such cases.
European Legislation
It soon became apparent in a close-knit Europe that legal cooperation is essential to facilitate free-trade commerce. Member States cannot afford in today’s world to shut themselves out going independent (much less stand alone and disjointed before the fledgling shadow of looming expansionist threats from territory-hungry countries led by power-lusted leaders fixated on a bygone era).
Having this in mind European legislators have wisely devised two legal mechanisms to streamline and implement swift legal procedures within Europe given all the cross-border legal issues that arose each year. These set of laws cover only well-defined civil and commercial matters.
i. The first one is Council Regulation (EC) Nº 44/2001, of 22nd of December 2000. Broadly speaking, this is used for court rulings which are deemed final and cannot be appealed. This procedure requires intermediate proceedings known as “exequatur” to be enforced which makes it more cumbersome and time-consuming than the one outlined below. It is hands down the more convoluted of the two which largely explains why lenders and creditors in general are more prone to use the below-listed EEO instead. In any case it has been superseded by Regulation (EC) 1215/2012 which shall apply to all legal proceedings instituted after the 10th of January 2015 and, amongst other key novelties, its main highlight features the abolition of the exequatur procedure.
ii. The second mechanism is the European Enforcement Order (EEO) Council Regulation (EC) 805/2004, of 21 April 2004. The EEO was devised some years later as a streamlined version of EC No. 44/2001 for uncontested claims and where a claim for the payment of a specific sum of money had fallen due. This procedure does not require an “exequatur”. It has proved wildly popular with Spanish lenders pursuing mortgage-related claims abroad for the reasons I explain further below in detail.
The above two legal mechanisms are binding laws for all Member States (except Denmark) including the United Kingdom (England & Wales, Scotland) and the Republic of Ireland.
Pursuing a Spanish Debt in the United Kingdom or in the Republic of Ireland
I. Council Regulation (EC) Nº 44/2001, of 22nd of December 2000
It boldly tackles the issue of recognising fellow EU member’s court rulings and enforce them in other EU Member States. The purpose of this regulation is to have these binding rulings directly applicable within the EU without any special procedure being required. By virtue of a principle of trust these rulings would be automatically and ‘immediately’ enforceable in another Member State without the law court being given the chance to review or challenge the foreign ruling being executed. In practice it takes several months, under a year, hinging upon the complexity of each case.
So basically there is almost no possibility for a UK or Irish High Court of Justice (Court of Session would be Scotland’s equivalent) to raise its own motion on grounds for non-enforcement or review of the matter at hand. Exceptions would be following Article 34 if the foreign ruling goes against the Public Order of the Member State being requested to recognise and execute the fellow EU Member State ruling or if the defendant has not been notified correctly of the legal proceedings being held against him.
Where to Sue?
As a general rule the criteria to sue someone, in accordance with Article 2 of this law, would be their domicile. So for example if you are domiciled in England, you ought to be sued in England & Wales, not in Spain.
However, for particular matters this general rule is waived i.e. repossessions
Case Study on Spanish Mortgages and Bank Repossessions
A mortgage against Spanish real estate is in legal terms a “Derecho Real” or right in rem. Following the above Council regulation, in Article 22 it stipulates that:
“The following courts shall have exclusive jurisdiction, regardless of domicile:
1. In proceedings which have as their object rights in rem in immovable property or tenancies of immovable property, the courts of the Member State in which the property is situated”
Following the above, a Spanish bank would sue you in Spain on defaulting a mortgage loan as the underlying property (immovable asset) is located in Spain.
On slipping into arrears on your Spanish mortgage, lenders may start to take legal action against you after three months (Law 1/2013). A lender will wait until you are technically labelled as “moroso” (defaulter) which takes place after 90 days of non-payment. For more details on a repossession procedure please follow my link on Bank Repossessions in Spain.
All those who sign a Spanish Mortgage deed, whether as borrowers or acting as guarantors (“avalistas”), may be held personally and unlimitedly liable for the mortgage loan with all their assets, both now and in the future, in compliance with Article 1911 of the Spanish Civil Code and specifically with Article 105 of the Spanish Mortgage Act.
Almost all Spanish Mortgage deeds establish that for legal notification purposes the borrower will be notified at the Spanish address on which the mortgage has been placed against, as it’s logical. This means that if you live for example in Ireland and your bank knows your Irish address and even spams you regularly with letters offering you additional non-requested financial services on repossessing you they would only notify you by recorded delivery at the mortgaged Spanish address. The fact that you receive no notification in Ireland or in the UK from the Spanish lender on initiating repossession proceedings, despite them knowing your home country’s address, does not invalidate the repossession procedure in any way. It will suffice prove of the lender having sent you by registered post notification of the start of legal proceedings against you.
Following my article on repossessions a lender would sue you in Spain. There is honestly little that can be done on falling into arrears other than paying all the owed amounts lump sum. These amounts may be considerable, as after 3 months of arrears the lender may tag on the bank’s lawyers fees (ranging between €10,000 – €15,000), court agent’s fees (several thousand), default compounded interest (ranging typically between 15-25% pa) as well as the arrears themselves.
You can at anytime stall a repossession procedure before there’s a ruling so long as you lodge the full requested amount lump sum before the court ruling hearing your case. Make sure you pay the correct amounts requesting from your lender a full breakdown of what’s owed calculated on a given date. Assistance by a Spanish lawyer is highly advisable.
Once a lender has attained a ruling against the borrower, which spans on average 1-3 years given how clogged law courts are in Spain, there are two possible outcomes:
a) If a lender adjudicates itself the property post-auction and there is an excess of equity the matter is settled and no-one will pursue you abroad.
b) The second option, likely the most common for technical procedural reasons explained in detail in my article on Spanish bank repossessions, is that post-auction there’s a shortfall on the amounts owed to a lender. Hinging solely on a lender’s decision (which will have a direct correlation on the amount owed by a borrower and any assets he owns within Europe) they may decide to pursue him for the shortfall in his home country.
Pursuing a debtor back at home
This is when Council Regulation 44/2001 comes into play. To follow this legal procedure, a Spanish ruling must be final, meaning it cannot be appealed to a higher court in Spain. As outlined above, there are very few reasons to appeal a repossession procedure as the matter is normally straightforward – the borrower has breached his fundamental obligation of servicing his mortgage repayments on time.
The lender will hire a local law firm to have the Spanish ruling recognised and executed in the borrower’s European home country. Some lenders may however decide to sell on their credit rights to a third party, such as a debt-collecting agency, who will from then onwards carry out a relentless chase up.
Some lenders are sending out nasty letters prior to obtaining a firm ruling in Spain. They are doing this to scare you into paying what’s owed hoping to avoid a protracted repossession procedure in Spain; it’s a bluff really as they cannot seize your home country’s assets until they have a ruling in Spain which is final (which takes on average 1-3 years).
Embargo and Execution
An embargo can only be placed on the portion of the house owned by the borrower. So if the property is owned jointly along with someone else and he/she did not sign the Spanish Mortgage deed, the charge only affects the borrower’s share. A sale of the house can be forced judicially if necessary (Oder for Sale). Bailiffs will embargo your worldly possessions to satisfy the debt.
If there is a first charge against the property, from a UK bank for example, the Spanish creditor’s charge will rank second place in priority.
Wages can also be embargoed leaving aside only the legal minimum stipulated by your home country laws. They will be paid directly to your creditor (Attachment of Earnings Order, AEO).
Bank deposits can also be frozen to satisfy the debt.
II. European Enforcement Order (EEO). Council Regulation (EC) 805/2004, of 21 April 2004
This Regulation offers significant advantages to creditors when compared with the exequatur procedure provided for in EC No. 44/2001 outlined above. Spanish lenders in particular are adept at employing EEOs as it has proved itself to be the swifter mechanism of the two as it does not require a ruling to be final (as opposed to EC No. 44/2001 which does and therefore takes longer to attain) nor is an exequatur required. In a nutshell the EEO greatly accelerates and simplifies access to enforcement in a Member State in which enforcement is sought by abolishing the exequatur (intermediate proceedings) thus saving time and expense.
EEOs are devised for uncontested claims where payment of a specific sum of money has fallen due. It proves ideal to chase secured debts such as those arising from mortgage-related debts.
Concept of Uncontested Claim
Pursuant to Article 3 a claim shall be regarded as “uncontested” if:
• the debtor has expressly agreed to it by admission or by means of a settlement which has been approved by a court or concluded before a court in the course of proceedings; or
• the debtor has never objected to it in the course of the court proceedings; or
• the debtor has not appeared or been represented at a court hearing regarding that claim after having initially objected to the claim in the course of the court proceedings; or
• the debtor has expressly agreed to it in an authentic instrument (i.e. a Mortgage deed witnessed by a Notary public).
Contesting a EEO
The competent court in the enforcing Member State may, subject to certain conditions, refuse to enforce a judgment if it is irreconcilable with an earlier judgment given in any Member State or in a third country. In certain cases, it can also stay or limit enforcement.
This is why I specifically mentioned earlier on that it’s important to keep tabs on the budding trend followed by Spanish law courts to dismiss chasing mortgage defaulters on grounds of negative equity borne by post-auction properties.
Pursuing a debtor in Spain
Likewise Spanish law firms are hired regularly by fellow European law firms and creditors to pursue assets located in Spain belonging to debtors using EEOs or else Council Regulation 44/2001. It works both ways as it’s a two-way street i.e. British creditors can enforce a EEO in Spain.
Conclusion: pursuing debts abroad is feasible albeit remains a matter of practicality
The urban legend that Spanish creditors cannot pursue, within the scope of the EU, debts abroad must be unreservedly quashed. Spanish creditors can and will pursue outstanding debts in the United Kingdom or in the Republic of Ireland. Another matter is if it is worth their while depending on the amounts owed. Bottom line is that it hinges really on a matter of practicality. In some cases it will be worth it and in others it won’t. On the former I strongly suggest hiring a lawyer to defend your interests.
It may take its time for a Spanish creditor albeit if they are resolute, and you own assets abroad, they’ll have their way eventually. And vive-versa, any British or Irish creditor can and will benefit from instigating European legislation to pursue and secure assets held in Spain by a debtor.
“We know the costs of Europe. What are the benefits?” – Nigel Farage.
British politician and leader of the UK Independence Party (UKIP)
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in inheritance, conveyancing, taxation and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
- Debt Recovery
- Recognition and Execution of Foreign Court Rulings
- Power of Attorney
- Land Registry Search (Nota Simple)
- Company Registry Search
Related articles
- Lifetime Loans or Reverse Mortgages in Spain Explained – 21st February 2011
- Advice to Struggling Mortgage Borrowers in Spain – 8th March 2011
- Spanish Mortgage Loans: Beware of Abusive Clauses – 8th January 2012
- Spanish Mortgage Loans: An Overview – 21st February 2012
- Mortgage Collar Clauses Revisited (‘Cláusulas Suelo’) – 8th December 2013
- Bank Repossessions in Spain – 21st February 2014
- Bad Debtor’s List (‘Fichero de Morosos’) – 8th April 2014
- Spanish Creditors Pursuing Debts Abroad – 8th May 2014
- Dación en Pago Explained or How to Hand Back the Keys – 8th December 2014
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarising, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
Bad Debtor’s List (‘Fichero de Morosos’)
Raymundo Larraín Nesbitt, April, 8. 2014
By Raymundo Larraín Nesbitt
Lawyer – Abogado
8th of April 2014
Introduction
Spain has ‘technically’ exited its seven year recession. However, the financial aftermath continues to look grim for most of the population (with the exception of our political class, of course). As a consequence, over 100,000 people are added each month to Spain’s dreaded bad debtor’s lists.
This article explains how you may be included in one of them (even unbeknownst to yourself!), the severe financial consequences this has (in Spain) and how to remove yourself from a black list.
What is a Bad Debtor’s List?
In Spain companies will include you on non-payment in a bad creditor’s list such as EXPERIAN, ASNEF or RAI which has dire consequences as it adversely affects your credit score and by extension hampers your future borrowing ability.
You may think that the people who are normally included in debtor’s black lists are in most cases professional non-payers or maybe families hit by the brunt of Spain’s financial downturn. However you would be surprised to learn there are multiple cases reported in which a person with a spotless credit track record is included out of spite by a company as a result of a legitimate dispute over a questionable invoice. At other times it may fall down to something as clumsy as a careless oversight on paying a service.
Examples:
- Your telephone company charges you €800 for roaming fees on a five-day trip to Egypt. Your mobile was switched off all the time. You refuse to pay until they give you an explanation. The mobile company declines explaining and blacklists you immediately.
- Your electric supplier increases your bimonthly invoice by 20% without providing a justified reason. You refuse to pay and are blacklisted as a result.
- You fail to close properly a Spanish bank account, or forget to top it up regularly, and slip into the red. The bank will blacklist you after a couple of months. Lenders take legal action for non-payment spanning between 3 to six months after the first arrears.
Consequences of being included in a Bad Debtor’s List
These consequences are financial and will severely hinder your borrowing ability in Spain, or elsewhere, in the near future. On being included in a black list you may be turned down on some or all the following:
- Personal loan
- Business loan
- Mortgage loan
- Consumer loan e.g. cards from major high street retailers that allow you fractioned or deferred payment over the next months. Kiss goodbye to your “El Corte Inglés” card.
- Credit card application
- Barred membership by selected retailers i.e. gyms, video clubs, golf clubs
Amount of the Debt
There is no minimum amount. Less than €100 warrants you being blacklisted.
Duration of the Inclusion in a Debtor’s List
The duration normally spans six years. After said time your details should automatically be removed by the registry.
What happens if I am not notified of my inclusion in a Bad Creditor’s List?
This is an entitlement. Failure to comply by the registry gives you good legal grounds to request a cancellation and a full withdrawal from the debtor’s registry. In practice this may be more difficult than I make it sound and you may need a lawyer to assist you.
Removal of a Debtor’s Registry
Paying off your debt will not have you automatically removed from a debtor’s registry. You must proactively pursue your own removal or else appoint someone qualified to do it on your behalf i.e. a lawyer. The whole procedure will only be carried out in Spanish language.
The Four Steps to remove oneself from a Bad Debtor’s Registry in Spain
- Pay off the outstanding debt which triggered your inclusion in the debtor’s list in the first place. Keep evidence substantiating the debt is fully settled (receipt, bank transfer, correspondence with the creditor etc.)
- Contact (in Spanish) the registry which have you black listed. Request a cancellation request form (“solicitud de cancelación”, in Spanish).
- Complete the form in Spanish supplying the registry with all the necessary evidence that unequivocally demonstrates the debt is now settled. You will have to send all by registered post (“burofax”) along with a copy of your passport / DNI (national ID card). The register will contact your creditor to confirm the debt has been settled to their satisfaction (there may be interests accrued or penalties that also need to be paid besides the principal itself).
- Once a registry has concluded their own internal investigation they should remove you within the next 30 days.
Conclusion Bad Debtor’s List (“Listado de Morosos”)
Spain’s ongoing delicate financial situation pushes families to the brink. The inclusion in a debtor’s black list may not be an issue if you are non-resident in Spain but becomes a serious matter for those holding resident status as it will seriously hamper their borrowing ability as well as being an overall nuisance in their day-to-day life.
I strongly recommend you to avoid an inclusion in such lists. And if you do happen to get included, a lawyer – for a reasonable fee – can help you to clear your good name by cutting through the red tape and language barrier in an expedient manner.
“I spent a lot of money on booze, birds and fast cars. The rest I just squandered” – George Best.
Northern Irish professional footballer. Winner of the European Cup with the Manchester United in 1968.
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in conveyancing, taxation, inheritance, and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
- Debt Recovery
- Recognition and Execution of Foreign Court Rulings
- Land Registry Search (Nota Simple)
- Company Registry Search
Related articles
- Lifetime Loans or Reverse Mortgages in Spain Explained – 21st February 2011
- Advice to Struggling Mortgage Borrowers in Spain – 8th March 2011
- Spanish Mortgage Loans: Beware of Abusive Clauses – 8th January 2012
- Spanish Mortgage Loans: An Overview – 21st February 2012
- Mortgage Collar Clauses Revisited (‘Cláusulas Suelo’) – 8th December 2013
- Bank Repossessions in Spain – 21st February 2014
- Bad Debtor’s List (‘Fichero de Morosos’) – 8th April 2014
- Spanish Creditors Pursuing Debts Abroad – 8th May 2014
- Dación en Pago Explained or How to Hand Back the Keys – 8th December 2014
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
Buying and Owning Spanish Property through Companies: Pros and Cons
Raymundo Larraín Nesbitt, March, 7. 2014
The pros and cons of buying and owning Spanish property through a company structure, off-shore or otherwise, by legal expert Raymundo Larraín Nesbitt.
By Raymundo Larraín Nesbitt
Director of Larraín Nesbitt Lawyers
7th of March 2014
Introduction
There was a time in which not a single Spanish law firm that prided itself would pass on the opportunity to heartily recommend its affluent non-resident client base (and even foreign residents) to acquire and own property in Spain by means of corporate structures ranging from the simple to the overtly complex often involving a multijurisdictional approach.
It was commonplace in the not-so-distant past to hear socialites in exclusive summer soirées on the coast boasting on how their law firm had devised and set up ingenious structures to the point that tax payment was negated and only a paltry sum was ever paid to the Spanish taxman.
Times change and legislation has moved on both in Spain and internationally since the events that led up to the tragic events of the 11th of September 2001. The war against international terrorism, unwaveringly led by the US, has meant intense pressure is exerted on the sources that finance it. These heartrending events coupled with 2008s financial sub-prime meltdown, and the ensuing world-wide credit-crunch, which left western countries’ coffers bereft, has meant that the once all-powerful and buoyant off-shore industry, now under intense scrutiny, has been forced to maintain a low profile in order to survive and accommodate to today’s imposed trends.
But even more fundamentally we have collectively assisted over the last decade not only to a change in laws but to a ground-breaking paradigm shift in social and moral values that no longer hold these structures as socially admissible as they are widely held in contempt by society and media at large i.e. the recent tax campaigns targeting Amazon and Starbucks amongst other high-profile companies.
You won’t find nowadays many Spanish-based law firms or lawyers actively recommending this option, much less clients boasting of their use. In fact, you will find many are even reluctant to the very idea and will likely try to dissuade you. This of course doesn’t rule out that it is still done, far from it, but it is not as widespread and most certainly not as openly publicized as before.
It is mostly foreign companies (which are not even law firms or FSA-regulated finance advisers!), located outside Spain, who now peddle a bespoke legal service offering “100% protection” to beneficiaries against Spain’s inheritance tax.
Spanish law firms located in Spain have been forced to take a back seat when it comes to offering and soliciting these legal services after new stringent legislation has been passed and tough obligations and controls have been set up across the board for lawyers and other professionals involved in their set up and administration.
Due to the enormous complexity of the matter, this article endeavours only to give a broad unbiased overview on the overall state of affairs, with particular focus in Spain, weighing in the pros and cons, albeit making no attempt whatsoever to delve in its complexity and most certainly being careful not to take stance on the matter one way or another.
Spanish Property Ownership through Corporate Structures
Advantages
1. Concealing Ownership
Several reasons may lead owners to conceal who really owns, controls and disposes of assets. Broad examples of such needs:
- privacy
- high-net-worth individuals (HNWI) have their wealth managed through companies run by family offices
- ongoing marital disputes which in time may lead to an eventual break-up and disposal of assets. Pre-empting such scenarios unfolding
- security reasons
- defaulting on contractual obligations abroad – avoiding asset-hunting through non-asset disclosure
2. Tax Mitigation
One of the traditional reasons that drive clients to seek incorporating structures is to lower their tax bill. From income and wealth tax to Spain’s cumbersome inheritance tax (ISD/IHT) corporate structures may allow at times the means to circumvent, in a legally accepted manner, footing hefty tax bills. The latter is particularly efficient when shareholders are non-residents.
These structures should ideally always be incorporated prior to acquiring the real estate asset, not after for optimum results. Careful forward planning is key from the outset on devising and incorporating them which should be tailored to each client’s particular needs. There are no magical one-size-fits-all schemes as clients’ needs differ widely from one another and even evolve in time with, for example, new family members or changes in their civil status (divorce).
Corporate structures range from the most basic ones to really ingenious ones that border on fiscal engineering. Law firms in Spain will have no qualms incorporating a Spanish or foreign company i.e. a UK limited liability company (as long as not offshore or located in tax haven). This is perfectly legal. They may even offer them off-the-shelf for a reasonable fee and additionally offer bookkeeping services. The company will then be placed on top of the Spanish real estate. They will however, following new legislation, be reluctant (understatement) when it comes to devising and incorporating more complex corporate structures, specifically offshore ones. This fine red line marks the difference between tax avoidance (legally acceptable tax planning) and tax evasion (criminally pursuable).
3. Asset Preservation
Affluent families have a mandate to preserve and accumulate wealth for future generations. Some corporate structures (i.e. trusts, which are not recognised in the Spanish legal system) help to achieve this by ‘protecting’ assets, even from their current beneficiaries, by legally separating the property’s legal ownership and control from its equitable ownership and benefits thus facilitating their transmission to future offspring. Trust dispositions may allow their use but will bar of their disposal as technically they no longer belong to their ‘owners’. We can imagine this as being particularly useful in the event of a divorce settlement (gold digger deterrent) as the assets are effectively locked-up in a corporate structure and cannot be disposed of being jealously guarded by the trustees in compliance with the trust’s dispositions. This is also useful over many generations as it allows keeping significant properties within the family’s control (i.e. Scottish ancestral castle).
Disadvantages
1. Concealing Ownership
New laws, most notably Law 10/2010 on Anti-Money Laundering and Finance of Terrorism, have created a vast array of new obligations for all those involved in the setting up of corporate structures, ranging from lawyers, civil servants (notaries), financial advisers to bank employees.
It is now mandatory that the ‘ultimate beneficiary’ of such structures is disclosed and clearly identified not only at the time of setting up new structures post 2010 but also – incredibly – on those that pre-date this 2010 law e.g. banks have been formally requesting to disclose beneficiaries as recently as January 2014 on structures incorporated a decade ago, long before these laws even existed.
So basically this law marked a turning point no longer allowing a fool-proof system that accommodated the warm mantle of anonymity i.e. bearer shares on multilayered off-shore structures. Anonymity is now achieved, yes, but to a certain extent only, at a basic level, as it limits the exposure to third-party information requests. So anyone requesting information from a Land Registry search will turn up with nothing (particularly if you’ve not made the mistake of appointing yourself as company director). However, it will remain glaringly visible to the Tax Office, or a judge, if needed be under this new law.
2. Tax Mitigation
Spanish lawyers and financial advisers are under great scrutiny and face stiff penalties, including severe jail terms, if found guilty on devising and collaborating in the set-up of tax avoidance structures. Every week we are treated with an unpleasant new story on how some prominent law firm or lawyer has been found guilty and charged.
For this reason alone Spanish lawyers and law firms in general are now highly reluctant to devise, assist, create or abet in any manner whatsoever such corporate structures. Much less to accept appointing themselves as administrators of said companies.
From a client’s perspective it is now debatable on whether such structures are able to mitigate or negate income or inheritance tax as efficiently as in the previous decade. It is open to debate.
New treaties, such as the Double-Taxation Agreement with Spain dating from 1976 has been recently amended in London on the 14th of March 2013 in an attempt to plug existing holes.
Additionally, and more worryingly, inspired by the US’s successful FATCA agreement, five European countries – including the United Kingdom and Spain – signed in April 2013 a pilot initiative enabling an automatic exchange of fiscal information which overall impact still remains to be seen. Traditionally European countries had the onus of undergoing protracted and expensive multijurisdictional investigations requesting information on a particular individual or company from other European countries to which not all complied with or the information supplied was often scant, incomplete and outdated. This pilot scheme no longer requires the signatory countries to actively pursue the information; it is actually fed back to them on a regular basis automatically on a wide range of companies and individuals falling within certain parameters. The possibilities this leads to on cross-referencing information are significant if done right.
Only this week we’ve learnt that the Spanish Tax office has approved that 40% of a tax inspector’s wage will be contingent upon results going forward. This creates a spectacular perverse incentive as now inspectors have truly a vested interested of their own in targeting tax avoiders. And corporate structures holding real estate assets is always a nice red flag in their eyes, whether true or not, as it has been traditionally considered a ‘wealth indicator’.
Some regions now incentivize and are more lenient, specifically on inheritance taxation, on having property under your own personal name rather than through structures which is being increasingly more taxed.
In the case of non-resident companies owning property in Spain and located in what the BoS lists as tax havens they attract a special annual tax equating to 3% of the property’s value. Art. 40 et seq. Spain’s Non-Resident Act 5, 2004.
In light of the ongoing recession and high levels of unemployment some European countries, i.e. Spain, are cash-strapped and have become increasingly more aggressive pursuing tax offenders. Not exactly the best of times to be setting up structures to mitigate taxes really.
3. Running Costs
Depending on the structure chosen this can range from several hundred euros a year for basic bookkeeping services to raking up dozens of thousands on more complex structures. You really have to ask yourself, given your wealth level and coupled with the value of the underlying asset, if you can actually afford or even if it is worth your while engaging in huge annual running costs on the long run that may even come to negate altogether any tax mitigation sought.
4. Who’s really in Control?
So many scary stories over the years it is hard to list them all. When you relinquish control of your asset through a power of attorney in favour of a physical person or a company abroad you better be sure of what you are doing and ensure you are fully aware of the risks this entails that may lead your beneficiaries to lose control of the asset upon your death.
Dispelling Spanish Inheritance Tax Myths
Scaremongering, a time-proven sales tactic. Car and insurance salesmen, in my experience, have always been top of the game at this because they know exactly what makes a customer tick. You will read plenty of scary stuff on ex-pat newspapers and internet on inheritance taxation in Spain which aims to prey on the gullible and harp on people’s inbred prejudices. I will try to cast away some of these widely held misconceptions.
Examples of such are:
1. “Spanish Inheritance tax legal fees can be at least 40 to 50%.”
False
Fact: On average inheritors pay in Spain 15% in inheritance tax. Only in the most extreme cases would you pay such a high amount. To give an idea, a single beneficiary that inherits over €800,000 would stand to pay 34%. Normally there are multiple beneficiaries to an estate; it’s not just one person that inherits all. Also the beneficiaries of the bulk of the estate are normally children, not non-relatives (which do not qualify for tax allowances). The significance this has is that the taxable base (the 800k) would then be split amongst the heirs dramatically reducing the IHT liability as it follows a sliding scale. To this you must also add the legal and family allowances (both national and regional) which reduce the percentage to be paid even further. Also worth mentioning is the fact that the taxable base for property is well-below the true market value.
I’ll put this in perspective with the most common example on British nationals inheriting in Spain. In my experience expatriates have second homes in Spain worth on average €400k. This property is normally owned in joint names meaning each spouse owns 50% of the property. On average couples have two children. So when one parent passes away, his 50% (the €200,000) is normally inherited by his two children. Therefore the taxable base of each child would be €100,000 (as the €200,000 is split equally between them). The surviving spouse naturally still owns his 50%. The state inheritance tax on a taxable base of 100k would be approximately €10,000 (10%). Children are classified in Group I for inheritance taxation purposes. The state tax-free allowance amounts to almost €16,000 for each child. In other words, the state allowance completely offsets the inheritance tax liability (meaning they pay nothing on inheriting in Spain in this example). Additionally children under 21 years old have further annual reductions with a maximum cap of €48,000. On top of this there are autonomous regional allowances that children may benefit from. So in this particular example, which in my professional experience I dare say is the most common, each children would stand to pay zero on inheriting a taxable base of €100,000 each. When the surviving spouse passes away the same result will unfold again providing the laws are not changed. So basically each child will have paid almost nothing on inheriting €200,000 each when both parents are dead.
On the other side of the spectrum, we can imagine a parent passing away bequeathing a €3,000,000 property to a single child or to a friend. In this particular case the inheritance liability would indeed sky rocket (over a million). For this particular case I strongly advise obtaining an estimation on the inheritance tax the beneficiary stands to pay. In this example it is definitely worthwhile looking into corporate structures to mitigate exposure to ISD/IHT as much as possible.
2. “Heirs will be forced to sell the property in Spain to pay off Spain’s extreme inheritance tax”
False
Fact: Same as previous point. Selling a property would be exceptional. In fact I’ve never come across a single client in over a decade that has been forced to sell to pay Spain’s ISD/IHT on inheriting. Moreover, you cannot inherit anything until you have first paid inheritance tax. So no-one can sell the property they are inheriting to then pay off the tax as the property is technically not theirs to sell as it is still under the deceased’s name. Only once the tax duties have been settled and the property is lodged under the name of the beneficiary at the Land Registry is he free to sell on if he wishes as the property is now legally under his name to do with it as he pleases.
3. “The financial debt of your heirs is maybe as much as 50% of the value of your property”
False
Fact: Everyone inheriting in Spain would then be broke. Same as the previous two bullet points, on average inheritors (beneficiaries) pay 15% for IHT/ISD in Spain.
4. “Yours husband or wife will not be exempt from Spanish Inheritance Tax.”
Misleading
Fact: Spouses indeed are not exempt from paying inheritance tax in Spain but they qualify for legal tax allowances. If resident in Spain then the surviving spouse is entitled to further autonomous regional tax allowances. These allowances, both from the state and from the autonomous region where the property is located, may greatly reduce the burden. Additionally if the surviving spouse is resident in Spain they may qualify for a 95% reduction on the main home providing they have lived in it the previous two years and keep it the following ten years (with a maximum reduction of €122,000).
5. “Want to avoid up to 81% of Spanish Inheritance Tax?”
Misleading
Fact: Scaremongers love quoting the extreme 81.6% tax rate for IHT as if this were the norm on inheriting in Spain. While it’s true that Spain’s inheritance tax can be as high as 81.6 pc – in the most extreme case – this only applies to the following case:
a) the beneficiary inherits > €800,000
b) the beneficiary is already well-off (his pre-existing wealth before inheriting > €4,000,000 or £3,000,000)
c) is a non-relative of the deceased classified in Group IV (no family ties to him i.e. a friend)
Clearly a problem affecting only a privileged few. Not a problem that the vast majority of beneficiaries inheriting in Spain will have to contend with unless they are already multimillionaires.
6. “If you incorporate a UK Limited Liability company and place the Spanish real estate inside you will be 100% shielded against Spain’s ISD/IHT. After death, only the shares are reorganised, the company owns the asset, and so it doesn’t change hands. This falls outside Spanish inheritance tax. Win-win”
False
Fact: Resident beneficiaries are obliged to pay inheritance tax under article 17 of Spain’s Inheritance and Gift Tax Royal on inheriting real estate within Spanish territory; regardless on whether the property is locked up or not within a holding company structure and regardless of whether you inherit the property itself or the shares. Likewise non-resident beneficiaries of a property located in Spanish territory also stand to pay Spanish inheritance tax (ex art. 18 of same decree) regardless if it’s in a holding structure or not. Moreover, I believe in the latter you may even be liable to attract UKs IHT beside Spain’s if the beneficiary happens to be a UK national.
Additionally Spain’s Non-Resident Act 5, 2004 clearly states that any re-arrangement of company shares (regardless of company’s nationality) which main asset is real estate located in Spain is taxable in Spain (CGT).
Depending on how clumsily this tax avoidance scheme is carried out it may be labelled as tax evasion (criminally pursuable for defrauded amounts above €120,000 ex art. 305 et seq. Spanish Criminal Code).
And to close I would like to take the opportunity to dispel a malicious misunderstanding on misreading one of my articles: Non-residents – Six Advantages of Making a Spanish will. Making a Spanish will does not reduce or mitigate your beneficiaries’ inheritance tax bill in any way whatsoever (as highlighted in the article itself). But it is extremely useful to save your beneficiaries time, money and hassle at a time of bereavement.
Without a Spanish will a beneficiary will normally incur in penalties and surcharges for late payment on inheritance in Spain. The reason for this is because there’s a deadline of 6 months as from the time of the testator’s demise to file and pay Spanish Inheritance Tax. UK probate, in my professional experience, always exceeds the six months deadline if there is no Spanish will. In which case penalties and surcharges are accrued and added to the inheritance tax for late payment. So ‘in a way’, making a Spanish will helps to mitigate or reduce the inheritance tax bill by way of helping not to attract said surcharges and penalties as the beneficiary is able to pay in time within the six-month deadline thus avoiding a lengthy procedure. I hope this clarifies the misunderstanding.
Spain’s Statutory Four-Year Tax Limitation
Another matter is if Spanish authorities do not get wind on the death of an owner who holds company shares, property or other assets. The statutory limitation of 4 years on all taxes, including Spanish Inheritance Tax, may kick in timing out the obligation to pay inheritance tax altogether – there is nothing the Tax Office can do after said time has elapsed to claim payment of inheritance tax from the beneficiaries. It should be noted that – exceptionally – the statute of limitation for Spanish Inheritance Tax is 4 years, six months and one day. In the particular case of a non-resident in Spain it is extremely difficult for the Spanish Tax Office (understatement) to know if and when they have passed away; unless of course his beneficiaries take to pro-actively inform the Spanish tax authorities… (or for that matter their bank in Spain; which also has the legal obligation to disclose the death to the tax office).
Pros and Cons of Owning Property in Spain through Corporate Structures – Conclusion
Generalisations are often dangerous and even more so on this delicate matter. The only sound advice that can be given is that a case-by-case study is required before any decision can reasonably be taken. Each client has different needs which evolve over time so structures may need to be changed to accommodate their changing needs i.e. post-divorce, new heirs, change in tax laws.
Different experts will give you different amounts or thresholds based on different reasons on whether it’s worthwhile or not to incorporate a company (or string of companies) for tax mitigation purposes. I would generally recommend only looking into corporate structures, for tax mitigation purposes, on a taxable base of €600,000 or above (£500,000). Note the use of the term ‘taxable base’. It is not referring to the value of the underlying real estate, but the amount that each beneficiary stands to inherit from the estate. Also note that the taxable base, when referring to property itself, is normally well-below the current market value of the property; it is not an up-to-date property appraisal.
So, for example, on inheriting an estate of €800,000 located in one of Spain’s seventeen autonomous regions that actually do tax inheritance tax and there is only one inheritor (beneficiary) then in this particular case I think it may be worth looking at getting quotations on setting up a structure to mitigate exposure to ISD/IHT. In Catalonia for example you would pay €350 in taxes (as resident) and if this estate were located in Andalucía the beneficiary would pay €164,000. This whopping difference that makes a beneficiary pay 469 times more in one region than another on the same estate is explained because autonomous regions in Spain are empowered to rule on inheritance tax.
Following on the same example set above, if instead we had three children (three beneficiaries) to inherit the €800,000 estate my answer would change and I think it would no longer be worthwhile. Because the taxable base would now be split between the three of them, thus reducing the attraction of the IHT rate band which follows a sliding scale. After legal and family allowances kick in there will be very little IHT to pay by each beneficiary not making it really worthwhile to incorporate a structure and to pay annual running maintenance fees for bookkeeping services and tax compliance purposes.
Not to mention that potential buyers normally refuse buying real estate locked up in holding structures out of fear of non-disclosed debts and hidden liabilities. A due diligence must normally be carried out prior to acquiring a company holding real estate to rule off such legal risks. To sell on a property, the vendor is normally required to first unwind the holding company (inheritors stand to pay for this) at a great expense to actually sell the underlying real estate itself.
Non-resident beneficiaries unfortunately do not benefit as much as those holding resident status when it comes to legal allowances to reduce the IHT taxable base as the applicable law is the state law (which is less lenient than regional tax allowances available only to residents). Admittedly non-residents unfortunately, and unjustly, still do not qualify to opt for the full range of tax allowances that residents are entitled to. The EU is looking into this as it is tantamount to discrimination with fellow EU member nationals – unacceptable.
EDIT May 2015: The EU ruled on the 3rd September 2014 on the matter in favour of non-residents ending all tax discrimination on inheritance matters. You can read my in-depth article Changes To Spain’s Inheritance And Gift Tax Law.
Inheritance tax planning in Spain is a complex matter, so please seek legal advice from a qualified lawyer and be wary of anyone advocating property ownership through corporate structures is “always beneficial” – not the case and in fact may be even be counter-productive and a complete waste of money. Beware of companies offering bespoke one-trick ponies to circumvent Spanish inheritance tax by offering “100% protection” against it.
If you fear Spain’s inheritance tax (IHT/ISD) you should first ask for en estimation from a law firm (we offer a SITAR service) before you do anything rash such as setting up a Spanish company or UK limited company to place it on top of the Spanish real estate. Inheritance tax varies widely within Spain’s seventeen autonomous regions (in some it’s not even taxed!). Truth is that corporate structures are neither needed nor recommended for the vast majority of people.
“We don’t pay taxes. Only the little people pay taxes” – Leona Helmsley.
US billionaire hotelier.
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in taxation, inheritance, conveyancing, and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Legal services Larraín Nesbitt Lawyers can offer you
- Conveyancing – Buying
- Conveyancing – Selling
- Off-the shelf-company
- Company Incorporation
- Company Registry Search
- Making a Spanish will
- Transfer of Estate to Heirs
Related articles
- Buying Distressed Property in Spain – 8th August 2011
- Non-Residents: Six Advantages of Making a Spanish Will – 8th August 2012
- Buying Resale Property in Spain – 21st February 2013
- Buying Off-Plan Property in Spain – 8th of June 2013
- Buying and Owning Spanish Property through Companies: Pros and Cons – 7th March 2014
- How to Buy Commercial Property in Spain – 4th July 2014
- How to Buy Rural Property in Spain – 8th August 2014
- How to Buy Property in Spain Safely – 10th October 2014
- Taxes on Selling Spanish Property – 8th December 2014
- Spanish Wills and Probate Law in Light of European Regulation 650/2012 – 8th January 2015
- Changes To Spain’s Inheritance And Gift Tax Law – 21st February 2015
- Dispelling Spanish Inheritance Tax Myths – 8th August 2015
- Spanish Inheritance Tax for Non-Residents (Part I) – 21st February 2016
- Spanish Inheritance Tax for Non-Residents (Part II) – 8th March 2016
- Inheritance Tax Novelties in Andalusia. FAQ on IHT – 8th September 2016
- Buying Property in Spain from a Private Seller – 21st of February 2017
- Buying Property in Spain from a Developer (Off-Plan Property) – 8th March 2017
- Which beneficiaries are hit worst by Spanish Inheritance Tax (IHT)? – 2nd June 2017
- Non-Resident: Why you need to make a Spanish will – 24th June 2017
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. VOV.
2.014 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
Bank Repossessions in Spain
Raymundo Larraín Nesbitt, February, 21. 2014
Spain’s property meltdown offers once-in-a-cycle investing opportunities through bank repossessions. The following beefed-up article from 2007 offers a complete legal overview.
By Raymundo Larraín Nesbitt
Lawyer – Abogado
21st of February 2014
Original article from 21st September 2.007
Introduction
The amount of home repossessions in Spain has soared to unprecedented levels according to the latest figures of the Bank of Spain. Conservative sources estimate the figure in well over 250,000 repossessions since the real estate market collapsed in 2007. The real number may actually be higher. This tidal wave has in turn spawned and exacerbated other phenomena such a new breed of middle-class squatters in Spain.
The Government, in denial mode, claims it has been overwhelmed and even caught off guard on the wake of recent social events. I beg to differ. Any industry insider would have told you at the time a sharp rise in repossessions was taken for granted for all the reasons collated below.
Underlying Causes of the Bank Repossession Crisis in Spain
The causes underpinning this surge in home repossessions are mainly related to the economic ‘recession’ Spain wades seven years on:
1. High levels of unemployment reminiscent of the Great Depression (an eye-watering 28% and counting) leading to widespread mortgage delinquencies. That is six million people unemployed. 1.8mn families in Spain have all their members unemployed. National youth unemployment (under 25-year-olds) is a staggering 55% and in some communities exceeds well over 60%. This quadruples the world’s average and doubles the European rate. These statistics, a human drama hiding behind each one, eerily echo harsh times straight out of a novel by John Steinbeck. Source: INE (National Institute for Statistics).
2. Aggressive reform in Labour laws which made dismissals less cumbersome and onerous overall. Spanish politicians pursue a ruthless internal devaluation at any cost to regain international competitiveness which translates into severe wage cuts. Less monthly disposable income edge Spanish families closer to the brink.
3. Unparalleled levels of lax lending. Bordering non-existent in the case of Spanish savings banks (‘cajas de ahorros’). Basically anyone with a pulse qualified for a mortgage loan.
4. Irresponsible property overvaluation led by bank-appointed appraisal companies.
5. Reckless over-indebtedness. Families should never spend more than 30% of their disposable income on servicing a mortgage loan.
6. Rising inflation. Traditionally offset by leading monetary institutions by increasing the price of money; that is by increasing the applicable interest rates.
7. Euribor rate poised to increase. It is used as a benchmark index in over 95% of variable interest Spanish mortgage loans reaching an all-time high in 2008. This means mortgage borrowers face the grim prospect of increased monthly repayments.
8. Relentless fall in property prices (on average 50% across the board) have discouraged potential purchasers, who postpone buying expecting even steeper discounts further down the line. Asset depreciation likewise affects existing property owners who find it hard to borrow against their properties unlocking equity through equity release schemes or life-time loans in Spain.
9. Severe credit shortage. The lowest on record on a fifty-year period aggravated by creeping interest rates and Spain’s uncertain financial health. In addition, bad credit for banks stands at a stunning 13%. The former helps to explain, amid other reasons I won‘t delve into, why Spanish lenders are reluctant to lend (unless at exorbitant borrowing costs which act as a deterrent grinding the market into a standstill). Credit is the real estate market’s lifeblood. If this is sapped away it creates huge imbalances. This effectively translates into scores of struggling borrowers being unable to offload a glut of properties in fire sales as keen would-be buyers are themselves turned down by tight-fisted lenders on applying for mortgage loans in a vicious gridlock that eventually drives the former to being repossessed. Mortgage borrowing costs in Spain are now at an all-time high. Cash is king.
10. Additionally, and specifically in the case of non-residents, the strengthening of the Euro against other currencies such as the Sterling Pound or the US Dollar makes it harder for these currency holders to face their monthly mortgage repayments in Euros.
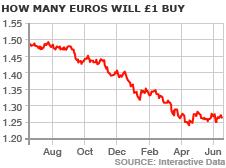
Definition of Negative Equity
A significant fall in property value translates into borrowers no longer being interested in servicing their mortgages as they have run into what’s known as ‘negative equity’ (they owe a lender more than what the property is worth).
How Can One Run into Negative Equity?
This takes place when the asset, or collateral, guaranteeing a mortgage loan is worth less than the loan amount itself.
Although this may seem difficult at first, the truth is that running into negative equity is surprisingly easy in Spain. In the following sections I explain how one attains negative equity:
i) steep drop in property price
ii) post-auction (repo) property
The reason why in nine out of ten public auctions in Spain no-one bids, besides the ongoing credit-crunch, is precisely negative equity. That is what’s keeping professional bidders at bay in such properties. Not all bank repos are a bargain, some are tripe; beware the hype. One should cherry pick them carefully assisted by a professional worth his salt (reputable estate agent, seasoned lawyer, expert investor).
I. Sharp Drop in Spanish Property Prices
The bank, on deciding if they will grant you a loan, will command an appraisal of the property on issuing a Binding Offer (‘oferta vinculante’). The property will act as collateral of the loan. If the value is unrealistic and is above the current market value of the property, should there be a fall in house prices, then a property may be worth less than the loan it is guaranteeing. This is the current scenario.
All mortgage contracts in Spain have a clause by which if the value of the property falls below 20% of the appraisal value the bank may request at their own discretion additional collateral to offset the financial shortage. In practice banks seldom opt to enforce it but they could legally.
In the event a lender seizes a property, it can auction it off publicly.
II. Public Auctions Mean a Further Drop in Property Price
As the influx of repossessed properties increases in the near future banks will eventually be forced to go through a public auction. In these auctions, should no-one bid, a lender is legally entitled to seize the property for 60% of its appraisal value. This has been recently increased by Law 1/2013 as before it was 50% which left the borrower in an even more precarious state.
Additionally, as I explain in detail further below, the extent of the liability is unlimited and personal. Meaning the lender will actually pursue the borrower for the outstanding unpaid amount (i.e. up to 40% plus associated repossession expenses).
This is precisely why overvaluing properties has turned out to be so harmful. Bloated appraisals have lead trustful borrowers to reel in shock as it dawns on them that the money fetched in a public auction falls well below the amount owed to their lender. On top of this you must also add the legal fees of the bank’s lawyers and the associated costs of a full-blown repossession procedure.
This is simply an injustice. As not only does a borrower stand to lose his property in an auction but must also withstand the additional aggravation of putting up with a lender that will relentlessly pursue him for the unpaid amount as the property value does not suffice to cover the loan amount plus mounting compound interests and associated repossession expenses. The debt will grow over time exponentially creating a debt spiral if left unchecked. This will turn many Spanish families into becoming lifetime financial pariahs; social outcasts with no hope of redemption.
Banks can legally pursue you abroad for a shortfall. Another matter is if it is worth their while.
Wait a Moment. I Have Already Paid X% of the Mortgage Capital During the Equivalent Period of Time!
Well, I’m afraid you haven’t! If your mortgage uses the French repayment method (as most of the mortgages granted in Spain do) then you will only have paid a small fraction of the mortgage capital upfront. The reason is that with the French system you pay interest-only during the early stages of a mortgage, as it gradually shifts to capital-only following a lineal sliding scale. This method is devised to allow that monthly payments terms remain fixed and equal throughout the duration of a mortgage.
To put it simply, during the first years of a mortgage you pay interest mostly. So if you default on the first years of a mortgage you practically have all the capital still outstanding to be paid off.
Extent of Liability
Following article 1911 of the Spanish Civil Code on signing a mortgage deed you will be held liable with all your current and future assets. This translates to unlimited personal liability. The debt goes personally against you, not against the property. The mortgage is only a guarantee subject to the financial loan with the property, or underlying asset, acting as collateral.
The above has huge legal implications which borrowers ought to fully understand before signing a Spanish mortgage deed. This means that if you default on servicing your Spanish mortgage, a lender may seize the property acting as collateral. If you fall into negative equity a lender is additionally entitled to pursue you abroad, even in your home country, for the shortfall. This may lead to a debt spiral – a very sticky situation.
Unlike in the UK and the US, most of the time handing back the keys to a lender will not stop them chasing you for the outstanding debt. This can only be achieved through a formal legal procedure known as ‘dación en pago’ which I care to explain further below.
Five Useful Tips to Avoid Repossession if you cannot Service your Mortgage
If you are struggling to meet your monthly mortgage repayments you should not wait until you have slipped into arrears to start negotiating with your lender. If you foresee falling into arrears, pre-empt the situation by requesting from your lender a debt restructure. After three months of mortgage arrears Spanish banks start to take legal action and initiate repossession proceedings.
Pre-repossession negotiations with a lender may include, but are not limited to, all the following:
1. Extend the mortgage repayments a number of years. The longer the duration, the less you stand to pay a month. The caveat is that you will end up paying considerably more in the long run due to the ‘magic’ of compound interest.
2. Reduce the interest rate or move on to an interest-only mortgage (‘carencia’) for a few years on the hope your economic circumstances will improve over time.
3. Apply for debt consolidation. This immediately reduces your monthly outgoings
4. Swap your mortgage to a new lender with less onerous conditions.
5. Attempt a property fire sale as a distressed asset (offering it at a steep discount).
If a borrower has unsuccessfully pursued any or all the above-listed debt restructuring options, he may consider handing over the keys to a lender only as an option of last resort. In doing this a borrower will avoid the dire consequences of a repossessions procedure; namely still being chased years after for a shortfall in the mortgage loan post-auction as outlined above. This is carried out following an ad hoc legal procedure, explained in the next section, rather than just allowing a lender to unilaterally repossess a property.

Do all properties end in a repossession?
Not all properties end in a public auction, especially in those few cases in which a borrower is not in negative equity. Those who have slipped into mortgage arrears may strike with their lenders an out-of-court-settlement which basically entails handing back the keys following a legal procedure. This is known as ‘dación en pago’ in Spanish.
This involves signing a deed at a Notary Public relinquishing ownership and in exchange a lender fully discharges a borrower of the remaining mortgage debt, not holding you liable in the future. The catch is that the property must not be in negative equity. This procedure is loosely modelled after article 140 of Spain’s Mortgage Act.
The whole point of following a dación would be to avoid repossession at all costs.
Sadly, as described in my updated article, ‘dación en pago finally a borrower’s right’, lenders no longer offer this option freely.
The Six Stages of a Bank Repossession
A repossession procedure generally follows in 6 steps:
1. The borrower falls into arrears – The borrower fails to service his mortgage repayments. Delay interests (‘intereses de mora’) accrue to cover penalties. The lender contacts the borrower and first attempts an out-of-court settlement.
2. In technical default – Three months from the first arrear (Law 1/2013). After 3 months in arrears a client’s file is passed onto the bank’s legal debt collection department which tries in a last-ditch effort to recover the debt. A lender will then initiate an Executive Procedure against the encumbered property filing it before a local ‘first court’ where the property is located. The bank is then forced to set aside a provision to offset the potential loss. This mandatory provision helps on to explain why lenders are open to negotiate before a default because these must be deposited before the Bank of Spain which undermines lenders’ liquidity ratios. Banks, with the ongoing current credit-crunch, will go to great lengths to avert this as it effectively hampers their own borrowing ability in the money markets. And credit is eventually shut to them leading to unpopular government bail outs.
3. Foreclosure and notary intervention – Depending on the chances of a debt recovery, 15 to 20 days after the technical default. A registered letter is sent by a Notary Public, with acknowledgement of receipt, informing a borrower that a repossession procedure is underway.
4. Repossession order – The court contacts the property owner to pencil a date for the trial. The judge notifies the borrower of impending repossession proceedings. The judge requests from the Land Registry a full report of charges and liens against the property. The value of the asset in the public auction can be either the one that is lodged at the Land Registry in the Mortgage deed or else the bank may command an updated appraisal. This updated appraisal will also be useful for the bank to decide on whether it is worthwhile or not to proceed with the repossession as this has high associated expenses. I must point out that a borrower may still successfully halt repossession at any time before the pencilled date for the auction so long as he pays the outstanding amount plus the full associated repossession expenses (easily over £8,000). These funds (outstanding monthly repayments with accrued delay interests plus the full associated repossession expenses) will have to be lodged both before the court that is ruling on the Executive Procedure before the date set for the auction. So time is of the essence.
5. The court sets a date for the public auction – Normally between 6 to 12 months after initiating the Executive Procedure. The judge sets the date of the auction. The value for auction purposes cannot fall below 75% of the appraisal value. However if no-one bids the gavel falls and a lender is legally entitled to seize the property for 60% of its appraisal value. The bank tries to recoup the outstanding loan debt instigating a public auction. However, post-repossession, after the property has been assigned to a winning bidder or to the lender; the amount fetched may not be high enough to cover the debt plus all the associated repossession expenses (i.e. because the borrower had run into negative equity). A lender will then be entitled to pursue the rest of the borrower’s assets, even if abroad, due to the personal and unlimited liability of a borrower ex art 1911 of the Spanish Civil Code. Should there be a guarantor on the mortgage deed the bank will chase their assets first it is easier to seize them. The property will now be lodged under the name of the new owner at the local Land Registry (normally the lender).
6. Eviction – In the event the now ex-owner still dwells in the property, after a period that normally spans six months, police officers will arrive at their door step with a locksmith and judicial bailiff to evict them by force, if necessary. There are a few instances in which delaying tactics may be employed albeit ultimately the outcome will be the same so it’s only buying time before the unavoidable.
Interested in Buying Repossession?
Repossessions offer great value for money. They are genuine unique investing opportunities as they have heavily built-in discounted prices for all the legal reasons explained above. Although repossessions offer the highest rewards to the undaunted they also have associated the highest risks. There is a clear correlation between risk and reward which a shrewd investor should ponder carefully in his decision-making before committing. The current market meltdown offers one-time buying opportunities that will likely take decades to be seen again. The timing is ideal for cash buyers who do not need to rely on a mortgage loan to acquire property. You will be spoilt for choice.
For more details read on my article on Buying Distressed Property in Spain which offers a detailed overview. It explains the different types of distressed asset classes, ranging from Non-Performing Mortgage Loans (pre-auction or key-ready properties) to Bank Repossessions (post-repossession properties) as well as the pros and cons of each. Repossessions are the real deal.
Spanish Bank Repossessions – Conclusion
Defaulting on a Spanish mortgage is a serious matter that may jeopardize your assets abroad as well as dealing a major blow to your credit rating score in your home country (hampering your future borrowing ability) as the debt will be against you personally and not against the asset itself.
Unlike in the UK, for example, in which we have a statute of limitations on debt after six years in Spain it works differently in practice. There is a statutory limitation of twenty-year years but it can be renewed at any given moment on the lender contacting a borrower to claim the principal plus compound interests accrued. Lawyers, acting on behalf of creditors, make sure to contact borrowers at regular intervals to avoid the limitation becoming firm. So in practice, never.
If everything else fails, the only option left is to try to negotiate with your lender. Lenders are open to renegotiate the lending terms providing you are not in arrears with them. Even borrowers saddled with debt should try to speak with their lender to find a way out. Lenders are reluctant to add yet another repossession to their books and so are keen to be flexible and accommodating.
To close I would like to imagine that lenders in general, and borrowers in particular, have learnt from the harsh lessons and in future cycles will avoid overstretching their finances saddling themselves with debt. Guessing it’s too much to ask for.
“Never was so much owed by so many to so few” – Sir Winston Churchill.
Eminent British career officer, artist, historian, and laureate writer – awarded the Nobel prize in Literature in 1953. Was even known to dabble in politics in his spare time; nobody’s perfect.
Larraín Nesbitt Lawyers, small on fees, big on service.
Larraín Nesbitt Lawyers is a law firm specialized in inheritance, conveyancing, taxation and litigation. We will be very pleased to discuss your matter with you. You can contact us by e-mail at info@larrainnesbitt.com, by telephone on (+34) 952 19 22 88 or by completing our contact form.
Mortgage-related articles
- Lifetime Loans or Reverse Mortgages in Spain Explained – 21st February 2011
- Advice to Struggling Mortgage Borrowers in Spain – 8th March 2011
- Spanish Mortgage Loans: Beware of Abusive Clauses – 8th January 2012
- Spanish Mortgage Loans: An Overview – 21st February 2012
- Mortgage Collar Clauses Revisited (‘Cláusulas Suelo’) – 8th December 2013
- Bank Repossessions in Spain – 21st February 2014
- Bad Debtor’s List (‘Fichero de Morosos’) – 8th April 2014
- Spanish Creditors Pursuing Debts Abroad – 8th May 2014
- Dación en Pago Explained or How to Hand Back the Keys – 8th December 2014
Please note the information provided in this article is of general interest only and is not to be construed or intended as substitute for professional legal advice. This article may be posted freely in websites or other social media so long as the author is duly credited. Plagiarizing, whether in whole or in part, this article without crediting the author may result in criminal prosecution. Voluntas omnia vincit.
2.007 and 2.013 © Raymundo Larraín Nesbitt. All rights reserved.
... Read more
